Ballarat, VIC 3350
Commercial & Business Loans Ballarat
We shop your deal to the lenders whose appetite actually matches it, build the file they want to see, and negotiate the terms rather than accepting the first offer. Talking through what your business needs costs you nothing.
The consumer protections you get on a home loan do not follow you into business lending. No Best Interests Duty, no responsible lending obligations, no Credit Guide. Your safeguards come from the contract instead, which is why we read the review points and the covenants with you before you sign.
What We Arrange for Your Business
We cover three broad categories: commercial property loans for buying premises or a commercial investment, equipment and asset finance for vehicles, machinery and plant, and working capital facilities for cash flow. Most of the businesses we deal with need more than one at some point, and we would rather structure them together than have you arrange each in isolation.
Borrowing for your business does not work the way borrowing for your home does. The protections are different, the paperwork is different, and the difference is easy to miss because the products look similar from the outside. We tell you which set of rules a facility sits under before you sign it, and we read the terms with you rather than leaving you to find out at a review point.
We work with operators across Ballarat and the surrounding shires, from single-vehicle trades through to practices and manufacturers carrying real plant. What we are not is your bank's branch lender: we are not tied to one balance sheet, so we can tell you when your existing bank is the right answer and when it plainly is not.
What It Costs You to Talk to Us
Nothing for the conversation. We will work out what your business needs, which lenders would look at it and what terms are realistic, at no charge and with no call-out fee. We will come to your premises anywhere in Ballarat or the surrounding shires for it.
How we are paid differs from residential lending and we tell you upfront. On most commercial and asset finance the lender or financier pays us a commission on settlement, and on complex or specialised deals a broker fee can apply. Where that is the case we quote it to you in writing before any work starts, and you decide whether to proceed. We will never present you with a fee you have not already agreed to.
Because business-purpose lending sits outside the consumer credit regime, the standard Credit Guide disclosure does not automatically apply to your facility. We disclose our remuneration to you in writing anyway, on every deal, so you can see what we earn from the lender we are recommending.
How We Shop Your Deal
Commercial terms are negotiated rather than published, so we build your file for a particular lender instead of sending the same application everywhere. You can stop at any stage.
-
01
We define the purpose and the security
Premises, equipment, working capital, or a combination. What the money does and what secures it decides which lenders we approach and which regulatory regime your facility sits under. We tell you which one that is.
-
02
We build your business case
Your trading history, financial statements, and for tenanted property the lease, meaning its term, the tenant quality and what happens at expiry. Commercial assessment reads the business and the asset rather than a scorecard, so we write the submission accordingly.
-
03
We approach lenders selectively
Every approach costs time and leaves a footprint, so we go to the lenders whose appetite matches your deal. That consistently produces better terms than testing the whole market and hoping, and it routinely takes us past the banks with a Ballarat branch to ones that have none.
-
04
We negotiate the terms, then read them with you
Rate, term, review points, covenants and any conditions attached to your security. We go through these with you line by line, because a business facility carries fewer automatic protections than a home loan and the review clauses are where the surprises live.
What We Need From You
- Two years of business financial statements and tax returns
- Recent BAS lodgements and business bank statements
- An aged debtors and creditors listing, if you are after working capital
- The lease, the contract of sale or the equipment quote, depending on what we are funding
- A short written summary of what your business does and what the funding is for
Talk Through Commercial & Business Loans Ballarat
Tell us what your business is trying to do and we tell you which lenders suit the deal, what deposit or security they will want, and what terms are realistic. Call us before you approach your own bank. Any fee is quoted in writing before we start.
Related Lending
Before You Call
What do you charge for business lending?
The conversation is free. On most commercial and asset finance the lender pays us a commission on settlement; on complex or specialised deals a broker fee can apply, and where it does we quote it in writing before we start work so you can decide. We disclose what we are paid on every deal.
What do you need from me to get started?
Two years of financials and tax returns, recent BAS and business bank statements, and a short written summary of what the funding is for. If you are buying property or equipment, add the contract or the quote. That is enough for us to tell you which lenders to approach and on what terms.
How long does a commercial approval take?
Longer than a home loan, commonly several weeks, because credit teams assess your business rather than run a scorecard and the valuation on a specialised Ballarat building can take time to arrange. We give you a realistic date up front and tell you which step is holding things up if it slips.
Will you come to my business?
Yes, anywhere in Ballarat and the surrounding shires, and there is no charge for it. On commercial work the site visit is often genuinely useful. Seeing the premises, the plant or the stock tells us things the financials do not.
Buying Your Own Premises
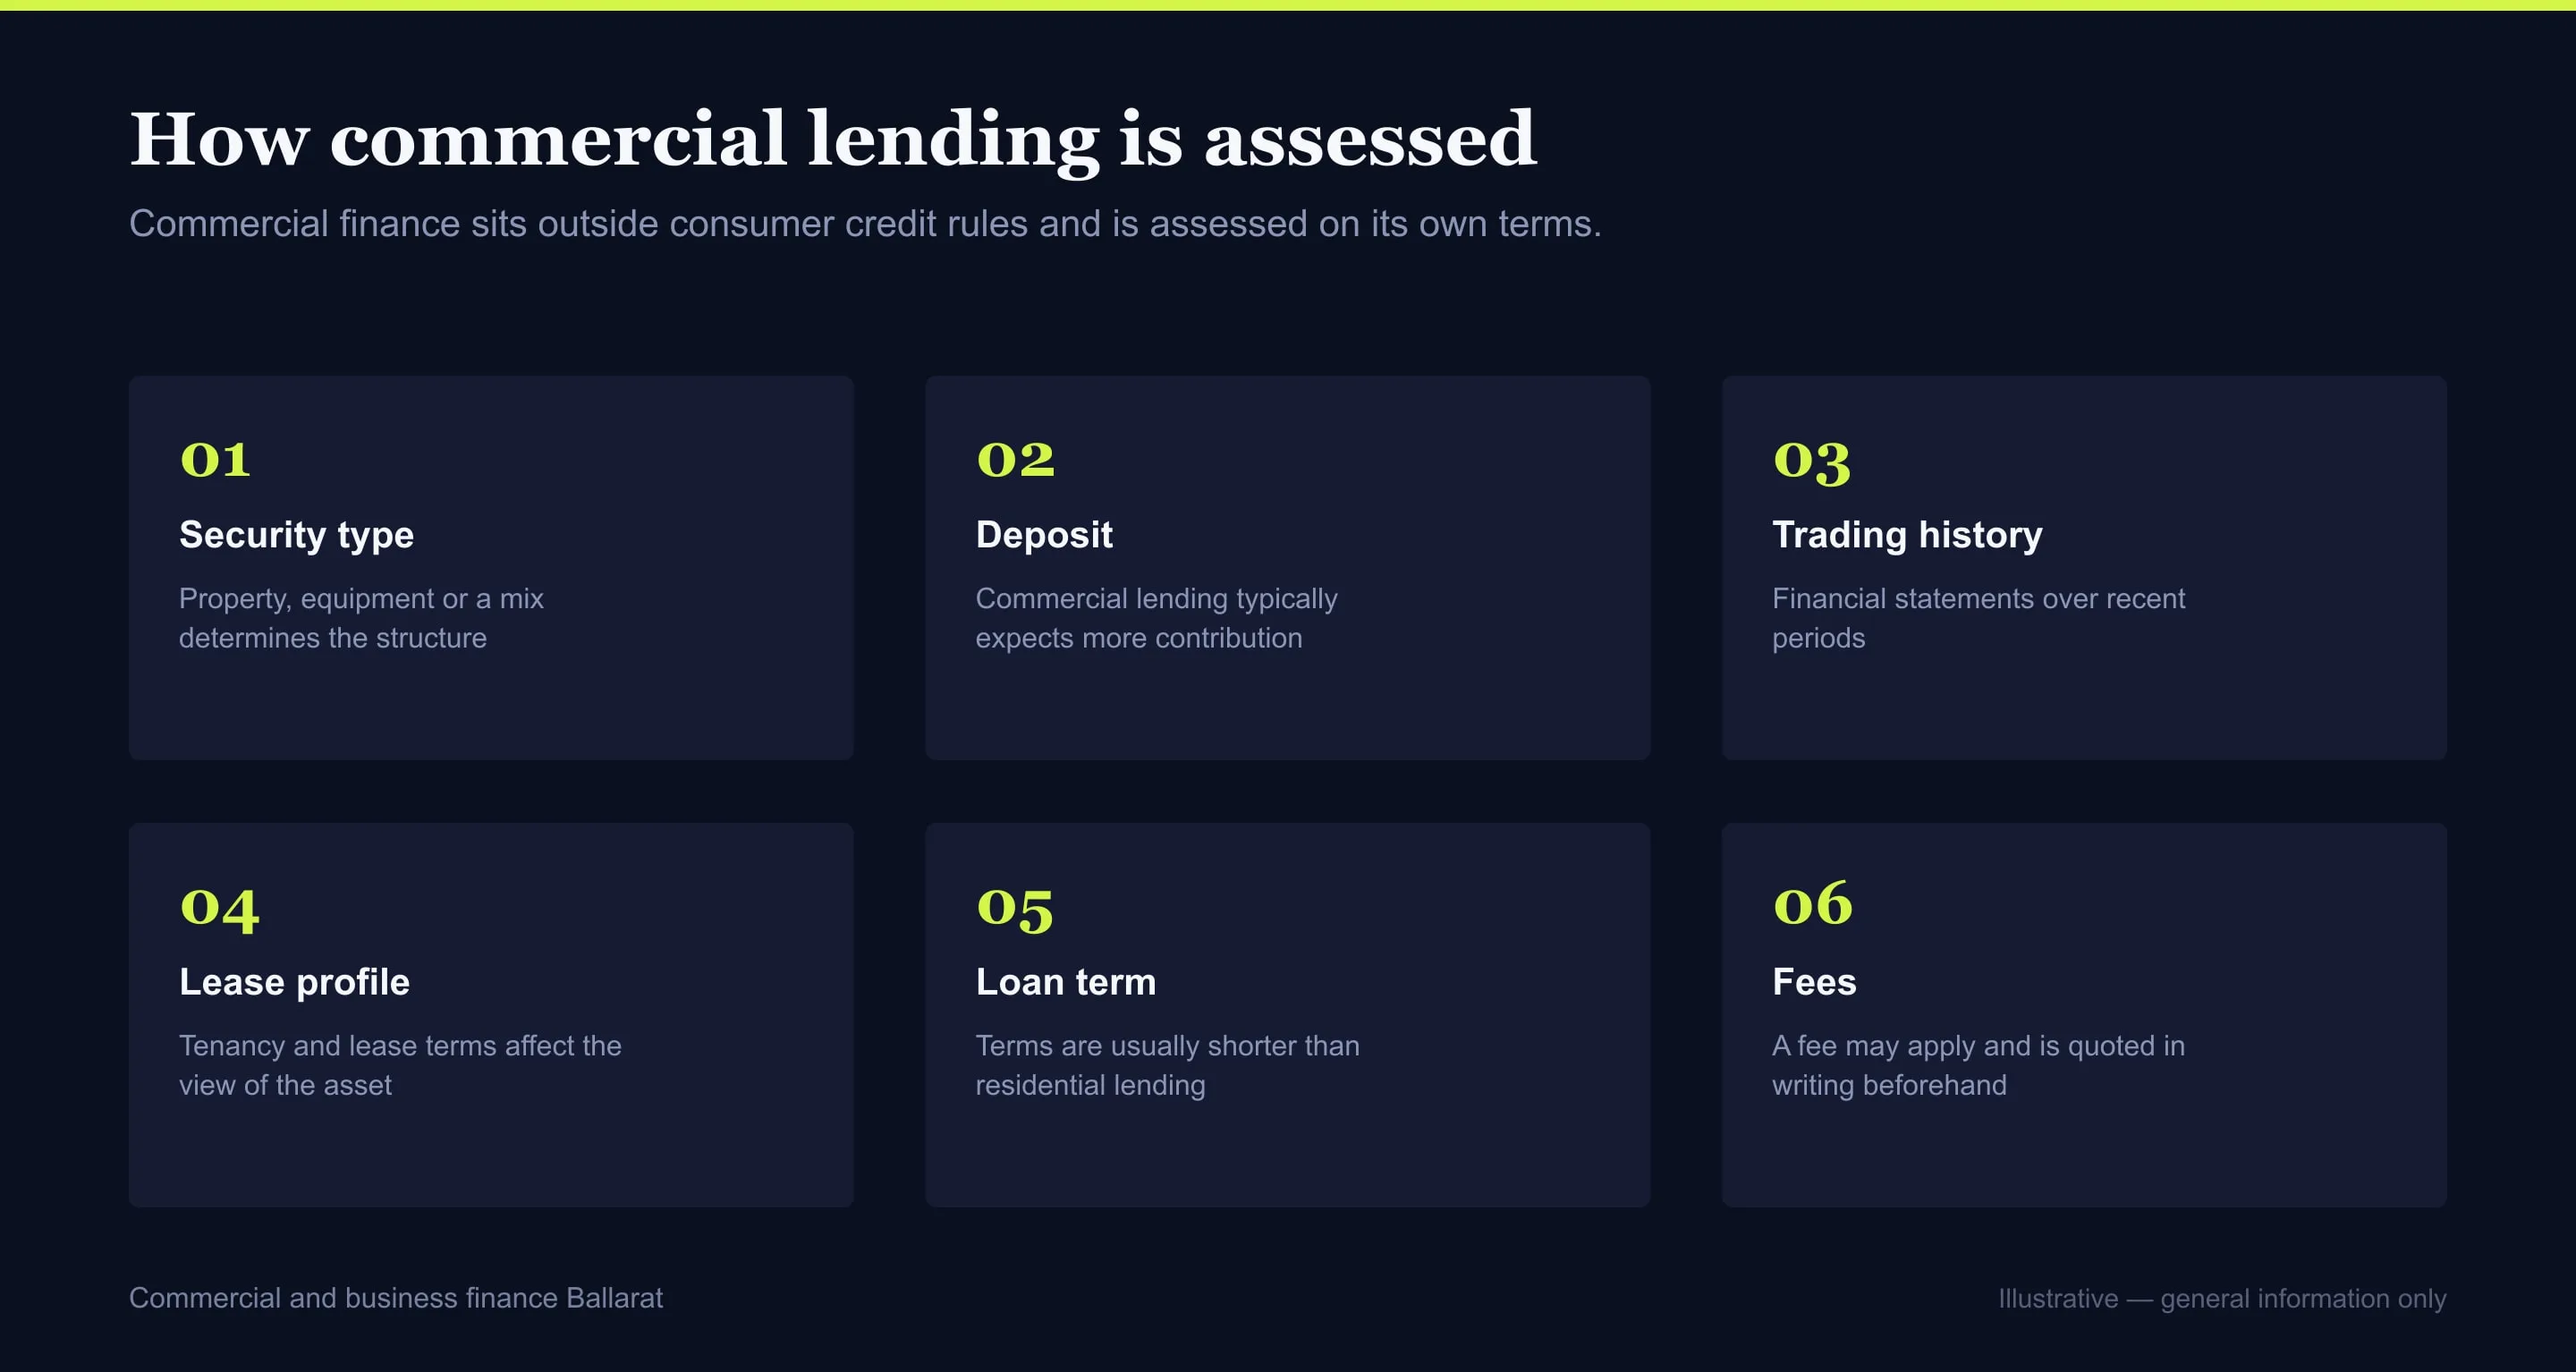
Buying a shopfront, warehouse, consulting rooms or industrial unit is assessed quite differently from buying a house, and the deposit is where you will feel it first.
Your deposit will be substantially larger than on a home. Where residential lending routinely runs to 80% or beyond with insurance, commercial property lending commonly caps around 65 to 70% of value, so budget roughly a third. We give you that figure before you start looking rather than after you have found the building. Terms are typically shorter than residential and pricing is set deal by deal instead of from a rate sheet, which is precisely why the deal needs negotiating rather than accepting.
The assessment looks at your business and the asset together. Lenders want your trading history and financial statements, and for tenanted commercial property they want the lease: its length, the quality of the tenant, and what happens at expiry. A property with a strong tenant on a long lease is a different proposition from a vacant one, and we present yours in the terms the credit team will be reading for.
How We Plan Around the Valuation
The valuation is worth planning for. Commercial comparables in Ballarat are thinner than residential ones, and a specialised building on the industrial estates may have very few genuine equivalents. Valuations therefore come back with a wider range of outcomes and take longer. We allow for that in the timeline we give you rather than promising a residential turnaround.
If you are considering buying your own premises through a self-managed superannuation fund, that is a specialised structure with its own rules and its own lending requirements. We can arrange the finance, but you need financial and legal advice specific to your situation before you commit to the structure, and we will tell you to get it.
Funding Equipment and Cash Flow
Not all borrowing involves property, and the shorter-term facilities are usually where your immediate need sits. We ask what problem you are solving before we assume it needs a mortgage.
Equipment and asset finance funds your vehicles, machinery, fit-outs and plant, usually secured against the asset itself. Chattel mortgages, hire purchase and leases are the common structures, and which suits you depends on how the asset is used and how you want it treated in your accounts. We will model the options and put them in front of your accountant, because the tax treatment is their call rather than ours.
Working capital facilities address timing rather than assets: overdrafts, business lines of credit, and invoice or debtor finance that advances against unpaid invoices. If your revenue is real but arrives later than your costs, that is the category we would point you at, and we will size it against your actual debtor days rather than a round number.
Plenty of Ballarat business owners borrow against residential property instead, because the rate is lower and the process is more familiar. That is legitimate and we arrange it regularly. But it puts your family home behind business risk, so we make you decide it deliberately rather than letting it happen as the default because it was easier to approve.
Which Rules Protect You, and Which Do Not
Your consumer home loan falls under the National Consumer Credit Protection Act, which brings responsible lending obligations, Credit Guide disclosure and Best Interests Duty with it. Business-purpose lending sits outside that regime, so none of those protections automatically apply to your facility and the documentation you receive is different. We make sure you know which regime you are in before you sign, because it changes what recourse you have later.
That does not mean business lending is unregulated. It means your safeguards come from the contract rather than from statute, so the terms carry more weight than they would on a home loan. We read them with you: the review points, the covenants, and the conditions that let a lender reprice or call in a facility. That beats discovering them when one is triggered.
Commercial Business Loans Ballarat Operators Need
We work across a genuinely diversified Ballarat economy. Health and education are anchored by the Base Hospital and Federation University, alongside manufacturing, retail, logistics, tourism and agriculture in the surrounding shires. That mix means we are not applying one template, and we will ask what your business actually does before suggesting a structure.
Population growth from people relocating out of Melbourne has supported demand for trades, professional services and retail across Ballarat, while the industrial areas and the highway corridor serve logistics and manufacturing. If your business is agricultural, your seasonal cash-flow pattern is something not every lender reads well, and we take those files to the ones that do.
Premises prices work in your favour compared with the capital. A shopfront or a warehouse in Ballarat costs a fraction of a comparable Melbourne building, which means the deposit that would only lease you space in the city can buy it outright here. That is the single most common reason the operators we deal with move from leasing to owning.
The lender who suits a medical practice buying consulting rooms is rarely the one who suits a transport operator financing trucks. Knowing which lender takes which view of a Ballarat business is most of the value in having us shop the deal rather than approaching your own bank first.
Should You Buy Premises, or Keep Leasing?
Owning removes your rent uncertainty, builds an asset and gives you control over the space. What it costs you is a deposit of roughly a third of the value, capital tied up in property rather than in the business, and responsibility for the building. We will put those numbers side by side for you before you decide.
Leasing preserves your capital and your flexibility, which matters most when the business is growing or your space requirement is likely to change. Rent stays an operating cost rather than a capital commitment, and if that is the better fit we will tell you so rather than arranging a purchase. Commercial vacancy in Ballarat is generally healthy enough that finding the next tenancy is not the obstacle it can be in a tighter market.
The call usually turns on how settled your business is and what else that capital could do. If your business would grow faster with the deposit deployed into stock, equipment or staff, we will say you should not be buying premises yet even where the repayment comparison looks favourable. Then we will look at funding the stock instead.
Commercial & Business Loans Questions
What deposit do I need for a commercial property loan?
Commonly around 30 to 35%, since commercial lending typically caps at 65 to 70% of value. It varies with the property type, the tenant and the strength of your business, and it is set deal by deal rather than from a table. We give you a realistic figure for your situation before you start looking.
Are business loans regulated like home loans?
No. Business-purpose lending sits outside the National Consumer Credit Protection Act, so responsible lending obligations, Credit Guide disclosure and Best Interests Duty do not apply in the same way. We tell you which regime your facility falls under before you sign, and we disclose our remuneration in writing regardless.
Can I use my home as security for a business loan?
Many lenders accept residential security for business borrowing, often at better pricing than unsecured business finance. It also puts your home behind business risk, so we make that a deliberate decision with you rather than a default, and we will suggest you take advice on it.
What is the difference between a chattel mortgage and a lease?
Under a chattel mortgage you own the asset from the start with the financier holding security over it; under a lease the financier owns it and you pay for use. The accounting and tax treatment differ, so we model both and send the figures to your accountant to decide.
How long do commercial loan terms run?
Generally shorter than residential, and often with a review or renewal point during the term rather than a set-and-forget structure. Terms vary widely by lender and facility, and we go through the review clauses with you before you sign because that is where the risk sits.
Who Reads the Terms With You
The person who answers is the one who works out which lenders suit the deal, what deposit or security they will want, and which regulatory regime the facility sits under. They then read the contract with you: the review points, the covenants, and what lets a lender reprice or call it in.
That reading matters more on business lending than on a home loan, because the contract is doing work that statute does on a home loan. Most of the deals we see here are secured against the family home, which makes the review and default clauses the ones worth understanding before you sign.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
Business lending across the Ballarat district, from equipment through to commercial property. Worth a call before you approach your own bank rather than after they have said no.