Ballarat, VIC 3350
First Home Buyer Loans Ballarat
Three separate forms of help exist for a first home in Ballarat, and each one has its own rules and its own price cap. The caps are what matter most, because between them they set the ceiling you can safely search under. Finding out where yours sits costs you nothing.
The check is worth doing before you start inspecting rather than after. A house that sits just over a cap costs you far more than the difference in its price, and by the time you have fallen for one it is too late for that to be useful.
What We Sort Out for First Home Buyers
Your first home loan is an ordinary home loan combined with whatever government assistance you qualify for. The loan itself is not special. The eligibility work is, and that is the part we do for you.
There are three schemes. The Victorian First Home Owner Grant is a cash grant for new homes. The stamp duty exemption cuts or removes the transfer duty you pay at settlement. The federal 5% Deposit Scheme lets you buy on a small deposit without paying Lenders Mortgage Insurance.
Different bodies administer them and each carries its own price cap, so we run your situation against each one in turn rather than assuming they move together. The caps are what usually decides your search range, well before the loan does.
You will usually call us at the point where you have some savings and want to know whether it is enough, and whether waiting another year would help or hurt. We will give you a straight answer on both, and we do this work for first home buyers across Ballarat every week.
What Our Help Costs You
Nothing. The lender pays us a commission when your loan settles, so the eligibility work, the borrowing figure and the scheme paperwork cost you nothing whether you go ahead or not. There is no call-out fee anywhere in Ballarat and no charge for the first conversation.
We put what we are paid in writing before you apply, in the Credit Guide we give you. That covers every lender we might recommend, so you can see the arrangement before you commit to anything.
Checking your eligibility does not touch your credit file and does not commit you to a lender. If we find you are better off waiting six months to build deposit, we will tell you that and it still costs you nothing.
How We Check Your Eligibility
We do this before you start looking, because it decides the price range worth searching in. You can stop after any stage without cost.
-
01
We run you against all three schemes
We assess the grant, the stamp duty concession and the 5% Deposit Scheme separately, and confirm each against the State Revenue Office and Housing Australia rather than against what was true last year. Schemes in this area change often.
-
02
We turn the caps into a search ceiling
Once we know which schemes apply to you, we give you a hard number to search under instead of a rough budget. We do this early because a property sitting just over a cap can cost you far more than the difference in price, and in Ballarat that line runs straight through the middle of the market.
-
03
We check your deposit will pass
We look at where your money came from and how long you have held it, and if a gift or a guarantor is involved we get it arranged and evidenced before we lodge rather than explaining it partway through.
-
04
We lodge the loan and the scheme together
We move your loan application and the scheme paperwork as one file, then chase it through valuation, approval and settlement so the two do not fall out of step.
What to Bring to the First Call
- Photo identification and your last few payslips
- Savings statements showing how you built the deposit, and over what period
- Details of any gift or guarantor support, and who is providing it
- Limits on any cards, car loans or personal loans you hold
- Whether you are looking at established homes or building new, because it changes which schemes are open to you
Talk Through First Home Buyer Loans Ballarat
Tell us where you are up to and we work out which schemes you qualify for, the price ceiling that follows from them, and what deposit you need to make it work. Call us if you would rather talk it through now.
Related Lending
Before You Call
What do you need from me to get started?
For the first call, just a rough picture: your income, your savings and how you built them, any debts or card limits, and whether you are looking at new or established homes. That is enough for us to tell you which schemes you qualify for and what price you can safely search under.
What happens if I turn out not to be eligible?
We tell you straight away, and we tell you what would change it: a few more months of savings history, closing a card, or looking at new builds instead of established homes. That advice costs you nothing, and we would rather you came back in six months eligible than lodged now and got declined.
Which Grants You Qualify For
The Victorian First Home Owner Grant is $10,000, and it is narrower than the coverage suggests. It applies only to new or substantially renovated homes valued at $750,000 or less, and established homes do not qualify at all. That single rule decides whether you should be looking at the growth estates or the established suburbs, so we settle it with you at the first call rather than after you have fallen for a house.
The larger $20,000 regional grant no longer exists. It applied only to contracts signed between 1 July 2017 and 30 June 2021 and it is closed, so if you have budgeted around it you are working from an out-of-date figure and we will rebuild your numbers without it.
The Victorian Homebuyer Fund is also closed to new applications, replaced by the federal Help to Buy shared-equity scheme. We check where Help to Buy sits at the time you apply, because a scheme that has changed since you last read about it is the most common reason a budget we are handed does not add up.
Which grant you can reach also depends on where in Ballarat you buy. The $10,000 is only available on new builds, so it is realistically in play on the growth estates on the western edge rather than in the established streets closer to the centre. We tell you which of your shortlisted suburbs can actually deliver it.
The Deposit Scheme Cap That Decides What You Can Buy in Ballarat
The federal Home Guarantee Scheme, now presented as the 5% Deposit Scheme, lets you buy with a 5% deposit and avoid Lenders Mortgage Insurance entirely. Since 1 October 2025 there are no income caps and places are unlimited, so the only real gate left is the price cap. We check that cap against the specific suburbs you are looking at before you start inspecting.
That cap is the figure most often got wrong, and getting it wrong costs you the scheme.
If you have read national coverage and assumed the higher figure applies here, you are working from the wrong number. The $950,000 cap covers Melbourne and Geelong, and Geelong is the sole designated regional centre in Victoria. We hold you to $650,000 because at that cap a large part of the local market is in range and anything above it takes you out of the scheme altogether, which usually costs far more than the price difference.
What You Will Pay in Stamp Duty
You pay no stamp duty at or under $600,000, a sliding concession applies between $600,001 and $750,000 that shrinks as the price rises, and above $750,000 you get no first home buyer concession at all. We calculate your duty at the actual contract price rather than the asking price, because that is the number that decides what you need at settlement.
Those thresholds have not moved since 1 July 2017 while prices rose, so the concession is worth less to you in practice than it was designed to be. With the median house price at $610,000 on the REIV Q2 2026 figure, a large share of local stock now sits just above the zero-duty line rather than below it. So we look at what is available on both sides of $600,000 rather than searching from the top down.
That produces a real decision at the margin, and we put the arithmetic in front of you: a property at $598,000 and one at $615,000 are much closer in purchase price than they are in total cost once duty lands.
What Deposit You Actually Need
Outside the guarantee schemes, most lenders want genuine savings, meaning around 5% of the purchase price accumulated in your own name and held for about three months. Money that appears suddenly is treated differently from money you have demonstrably saved. We look at your savings history early, because the shape of it decides which lenders will accept your deposit at all.
A gift from family or a guarantor arrangement can substitute, but lenders assess those differently and not all accept them on the same terms. If you are relying on either, we get it established and evidenced before your application goes in, rather than trying to explain it to an assessor halfway through.
Should You Use the Scheme, or Save a Bigger Deposit?
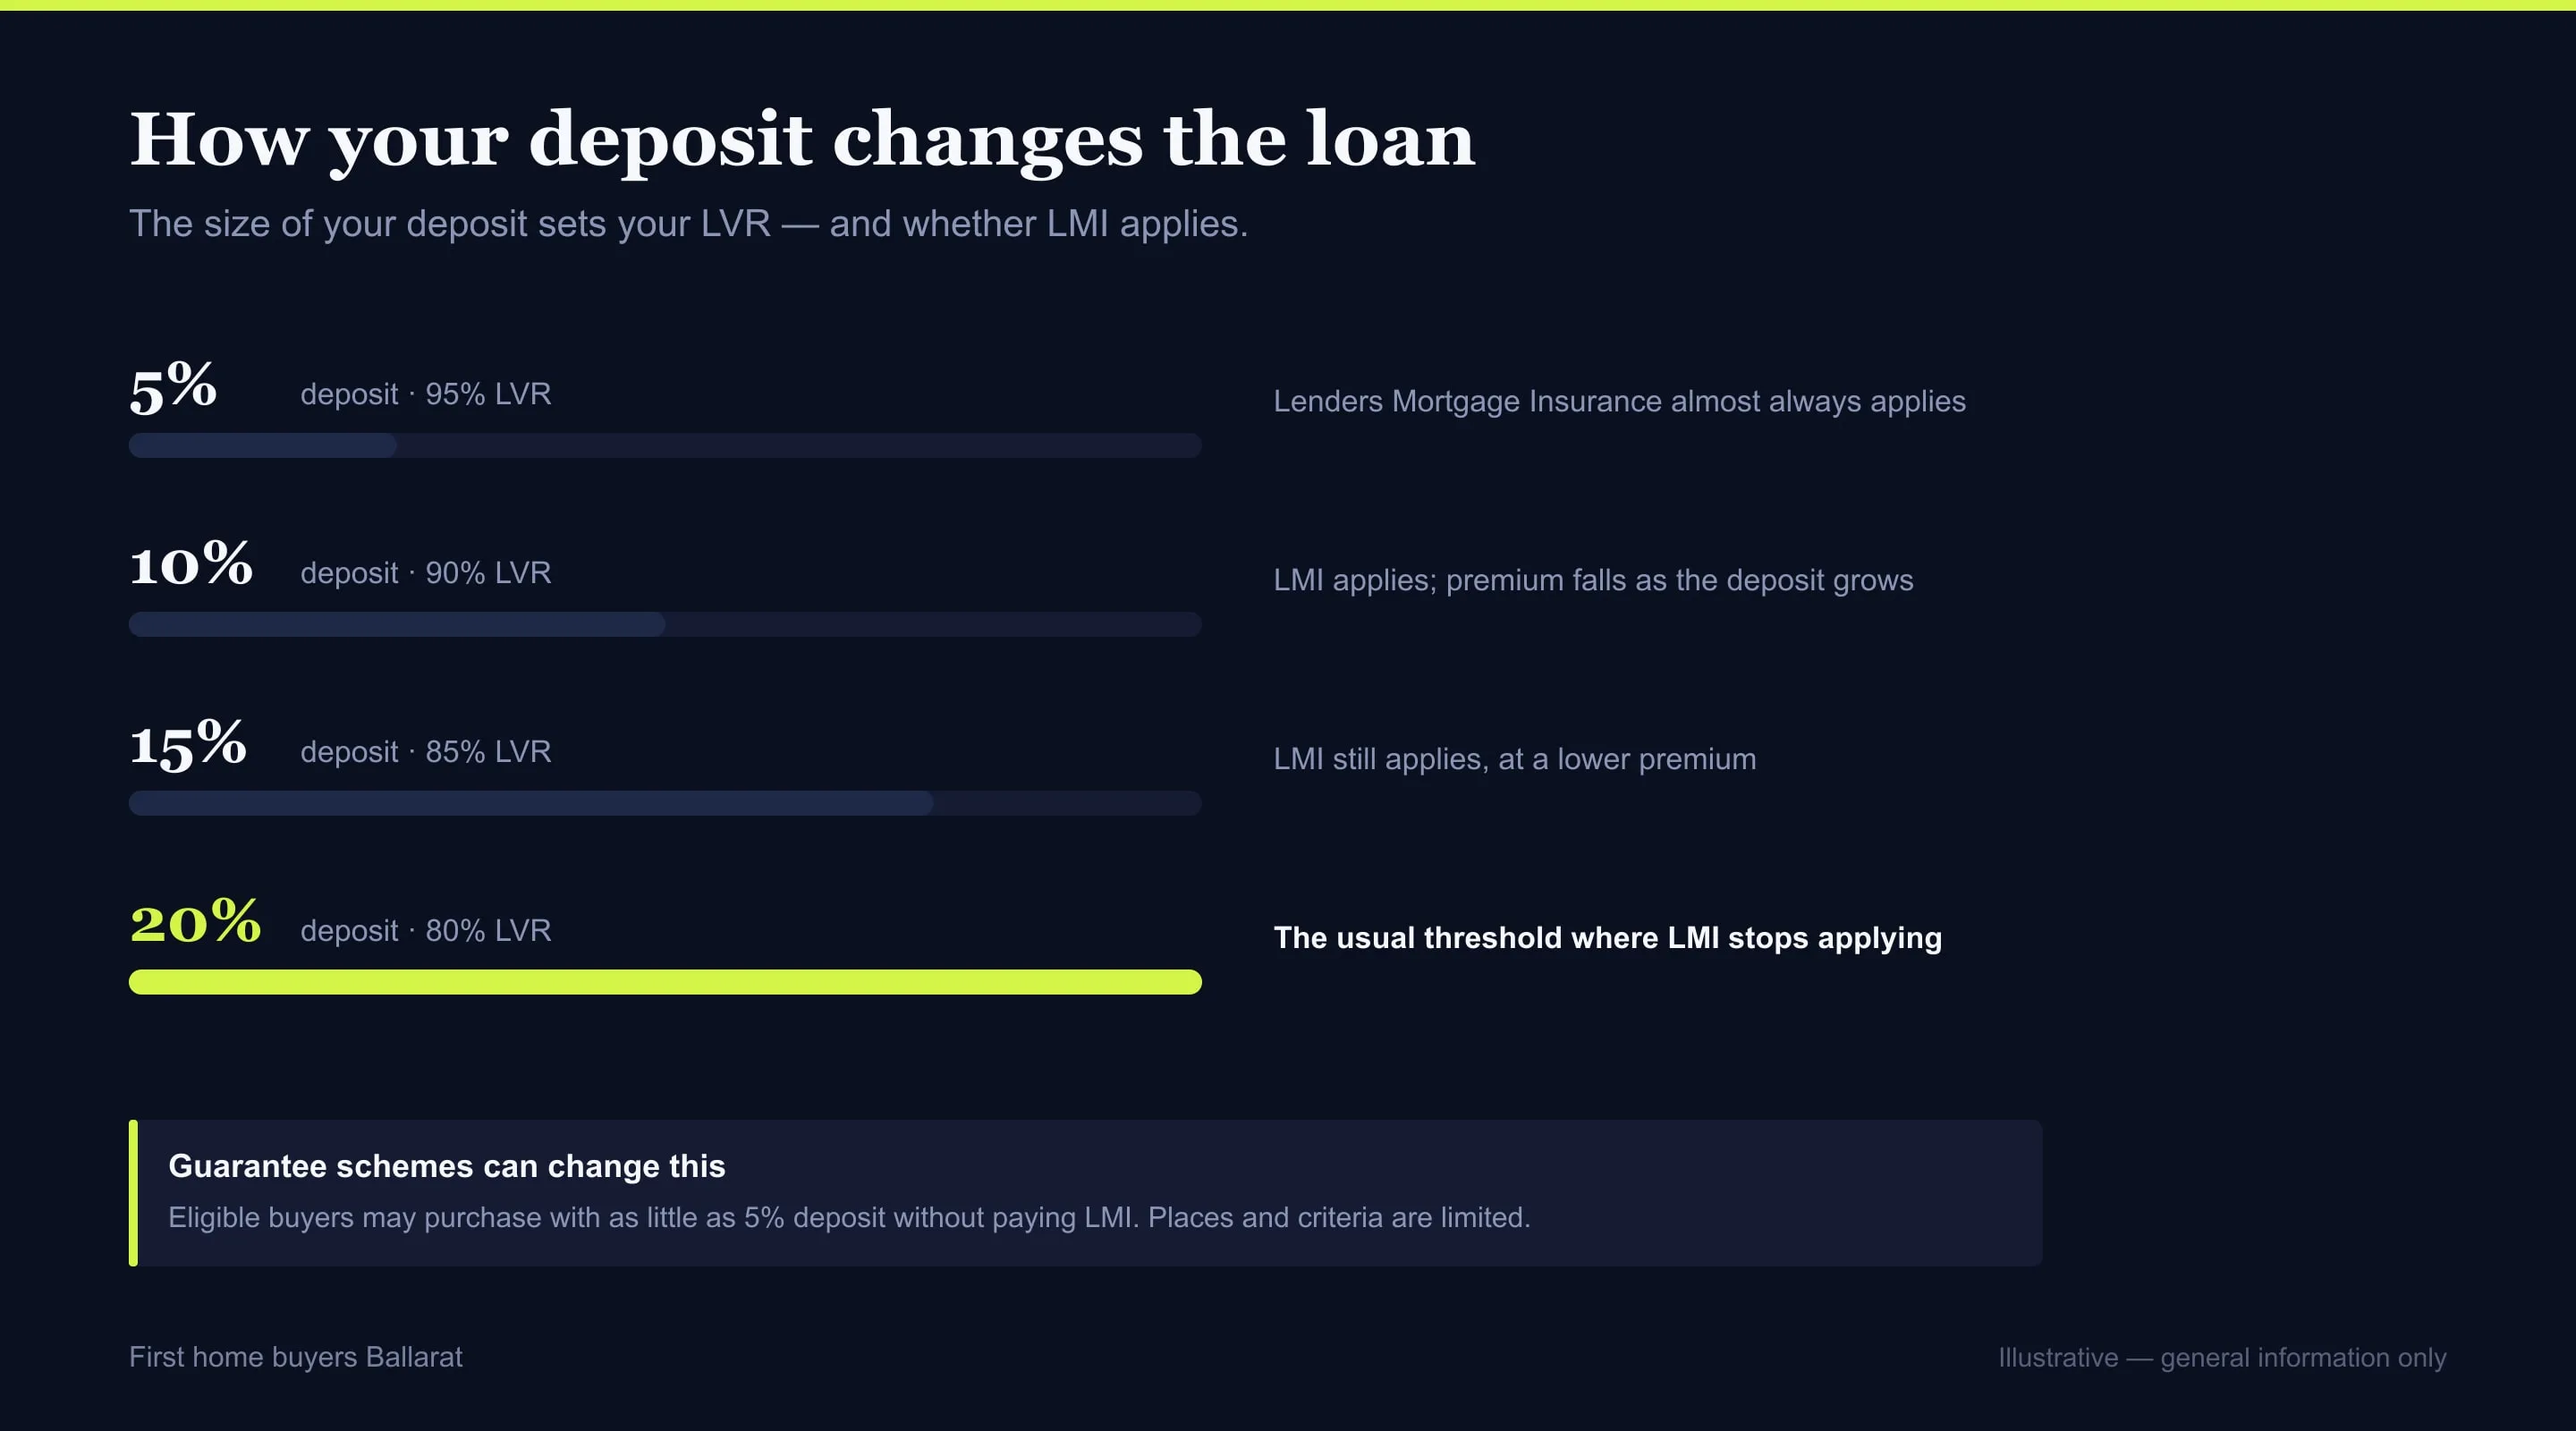
The 5% scheme gets you in sooner and avoids Lenders Mortgage Insurance entirely. The trade-off is a larger loan, higher repayments and less equity buffer if prices move against you. We model both paths and show you the repayment difference before you choose.
Saving to 20% avoids all of that but takes time, and in a rising market your deposit target moves while you save. Three things decide it, and we check all three with you: how secure your income is, how fast you can actually save against a moving target, and whether the properties you want sit under the $650,000 cap.
Your other live decision is new versus established, and we will tell you which way your circumstances point. Only new or substantially renovated homes attract the $10,000 grant, which pushes you toward the growth estates on the western edge of Ballarat; established homes closer to the centre forgo the grant but avoid the timeline and contract risk of building.
First Home Buyer Loans Questions
Do I qualify for the $10,000 grant in Ballarat?
Only if you are buying or building a new or substantially renovated home valued at $750,000 or less. Established homes do not qualify for the First Home Owner Grant in Victoria, so we settle whether you are buying new or established before we build your budget around the grant.
Is there still a $20,000 regional grant?
No. The $20,000 regional First Home Owner Grant applied only to contracts signed between 1 July 2017 and 30 June 2021 and it is closed. The current Victorian grant is $10,000 for new homes, and we will rebuild your figures on that basis if you have been planning around the old number.
What is the 5% Deposit Scheme price cap in Ballarat?
$650,000, because Ballarat is treated as regional Victoria. The higher $950,000 cap applies to Melbourne and Geelong only, and Geelong is the sole designated regional centre in the state. We check the cap against the suburbs on your list before you start inspecting.
Can I combine the grant, the scheme and the stamp duty exemption?
These are separate programs with separate eligibility and some buyers qualify for more than one. The price caps differ between them, so a property can fall inside one and outside another. We map your position across all three, and we confirm it against the State Revenue Office Victoria and Housing Australia before you commit.
How much deposit do I actually need?
Under the 5% scheme, 5% plus costs. Outside it, most lenders want genuine savings of around 5% held for roughly three months, and below 20% you will generally pay Lenders Mortgage Insurance. We tell you which of those applies to you and what the gap is in dollars.
Who Works Out Your Scheme Eligibility
The person you speak to is the one who checks you against the grant, the stamp duty concession and the federal deposit scheme, then keeps the file through to settlement. They do that check before you start inspecting, because the answer decides your price ceiling rather than just your paperwork.
It is worth having one person hold all three. Each scheme has its own rules and its own price cap, and they interact in ways that are easy to get wrong from the government pages alone. Qualifying for one tells you nothing about the others, and we would rather work that out for you now than have you discover it at contract.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
If you are buying your first home in Ballarat, the eligibility check is worth doing before you start inspecting rather than after. It sets the price you can safely search under.