Ballarat, VIC 3350
Home Loans Ballarat
We arrange home loans Ballarat wide, and the first thing we do is tell you what you can actually borrow. Not the calculator figure. The one a lender will sign off, after the buffer, your card limits and the expense benchmark have all done their work on it.
That number moves more between lenders than it does between rates. The same payslips can land thousands apart depending on whose policy reads them, so we run your figures across a panel before you commit to a price.
What We Do on a Home Loan
We hold an accreditation panel of lenders and work out which of them will lend to you on the best terms available for your circumstances. That runs from the first borrowing-power conversation through to the day your loan settles.
The work splits into three parts. We establish what you can borrow, we match your situation to lenders whose policy suits it, and we prepare an application that will not stall in assessment. Which of those matters most depends on you. A clean salaried file needs the third. A self-employed file needs all three.
You will usually reach for us at one of three points: before you start looking, after a bank has said no, or when the loan you already have no longer suits you. Any of those is a reasonable time to pick up the phone, and we take enquiries from right across Ballarat and the surrounding shires.
What It Costs You to Call Us
Nothing. On almost all residential lending the lender pays us a commission when your loan settles, so our time costs you nothing whether you proceed or not. There is no call-out fee anywhere in Ballarat and no charge for the first conversation.
We tell you in writing what we are paid before you apply. That disclosure sits in the Credit Guide we give you, and it names the commission arrangement on every lender we might recommend. If a fee ever did apply to your file, you would see it in writing there first and you could walk away at that point.
You are also free to stop at any stage. If we work out your number and you decide to wait a year, that is a normal outcome and it costs you nothing.
What Happens After You Call Us
We work through four stages with you, and you can stop after any of them without cost.
-
01
We work out what you can borrow
We go through your income, existing debts, card limits and deposit, then come back to you with a figure you can rely on. Nothing is lodged at this point and nothing touches your credit file, so there is no downside to finding out.
-
02
We match your file to a lender
We check your situation against the policy of each lender on our panel: how they treat your income type, where your deposit came from, and the property itself. Policy differences rule most of the panel out quickly, which is exactly why we do this before you apply rather than after.
-
03
We set the structure with you
Fixed, variable or split. Offset or redraw. Whether to fix part of your balance and leave the rest moving. We settle these with you now because unwinding them after approval is slow and sometimes expensive.
-
04
We lodge it and chase it through
We assemble your file, submit it, then follow it through valuation, formal approval, loan documents and settlement. Every stage carries a lender-side wait, and we answer the assessor's questions inside the submission so your file waits the least. Valuers covering Ballarat book out at busy times, which is the one delay we plan around rather than absorb.
What We Need From You
- Photo identification for every applicant
- Recent payslips, or business financials and notices of assessment if you work for yourself
- Bank statements covering the last few months
- The limit, not the balance, on every card you hold, and the repayment on every loan
- A realistic figure for what your household spends each month
Talk Through Home Loans Ballarat
Tell us where you are up to and we work out what you can borrow, which lenders suit your situation, and what your deposit position means for Lenders Mortgage Insurance. Call us if you would rather talk it through now. The conversation costs you nothing either way.
Related Lending
Before You Call
Do I pay you anything?
No, in almost all residential cases. The lender pays us a commission when your loan settles, so there is no direct cost to you and no charge for the first conversation. Where a fee does apply we disclose it in writing in the Credit Guide before you apply, so you see it before you commit to anything.
What do you need from me to get started?
For the first call, nothing formal. A rough idea of your income, your debts and card limits, and what deposit you have is enough for us to give you a working figure. If you decide to proceed we will ask for photo identification, recent payslips or business financials, and a few months of bank statements. We can take all of that over the phone or in person anywhere in Ballarat.
How long does a home loan take?
From first call to formal approval is commonly a few weeks, though it varies by lender and by how complete your file is when we lodge it. Valuation and lender assessment queues are the two waits we cannot compress, and valuer availability in Ballarat can stretch the first of those; a file that answers the assessor's questions upfront is the part we can control.
What happens if I am not eligible right now?
We tell you plainly, and we tell you what would change it: closing a card, waiting for another year of financials, or building a bit more deposit. We would rather give you a short list of things to fix than lodge an application that gets declined and leaves an enquiry on your file.
What Changes Your Borrowing Power
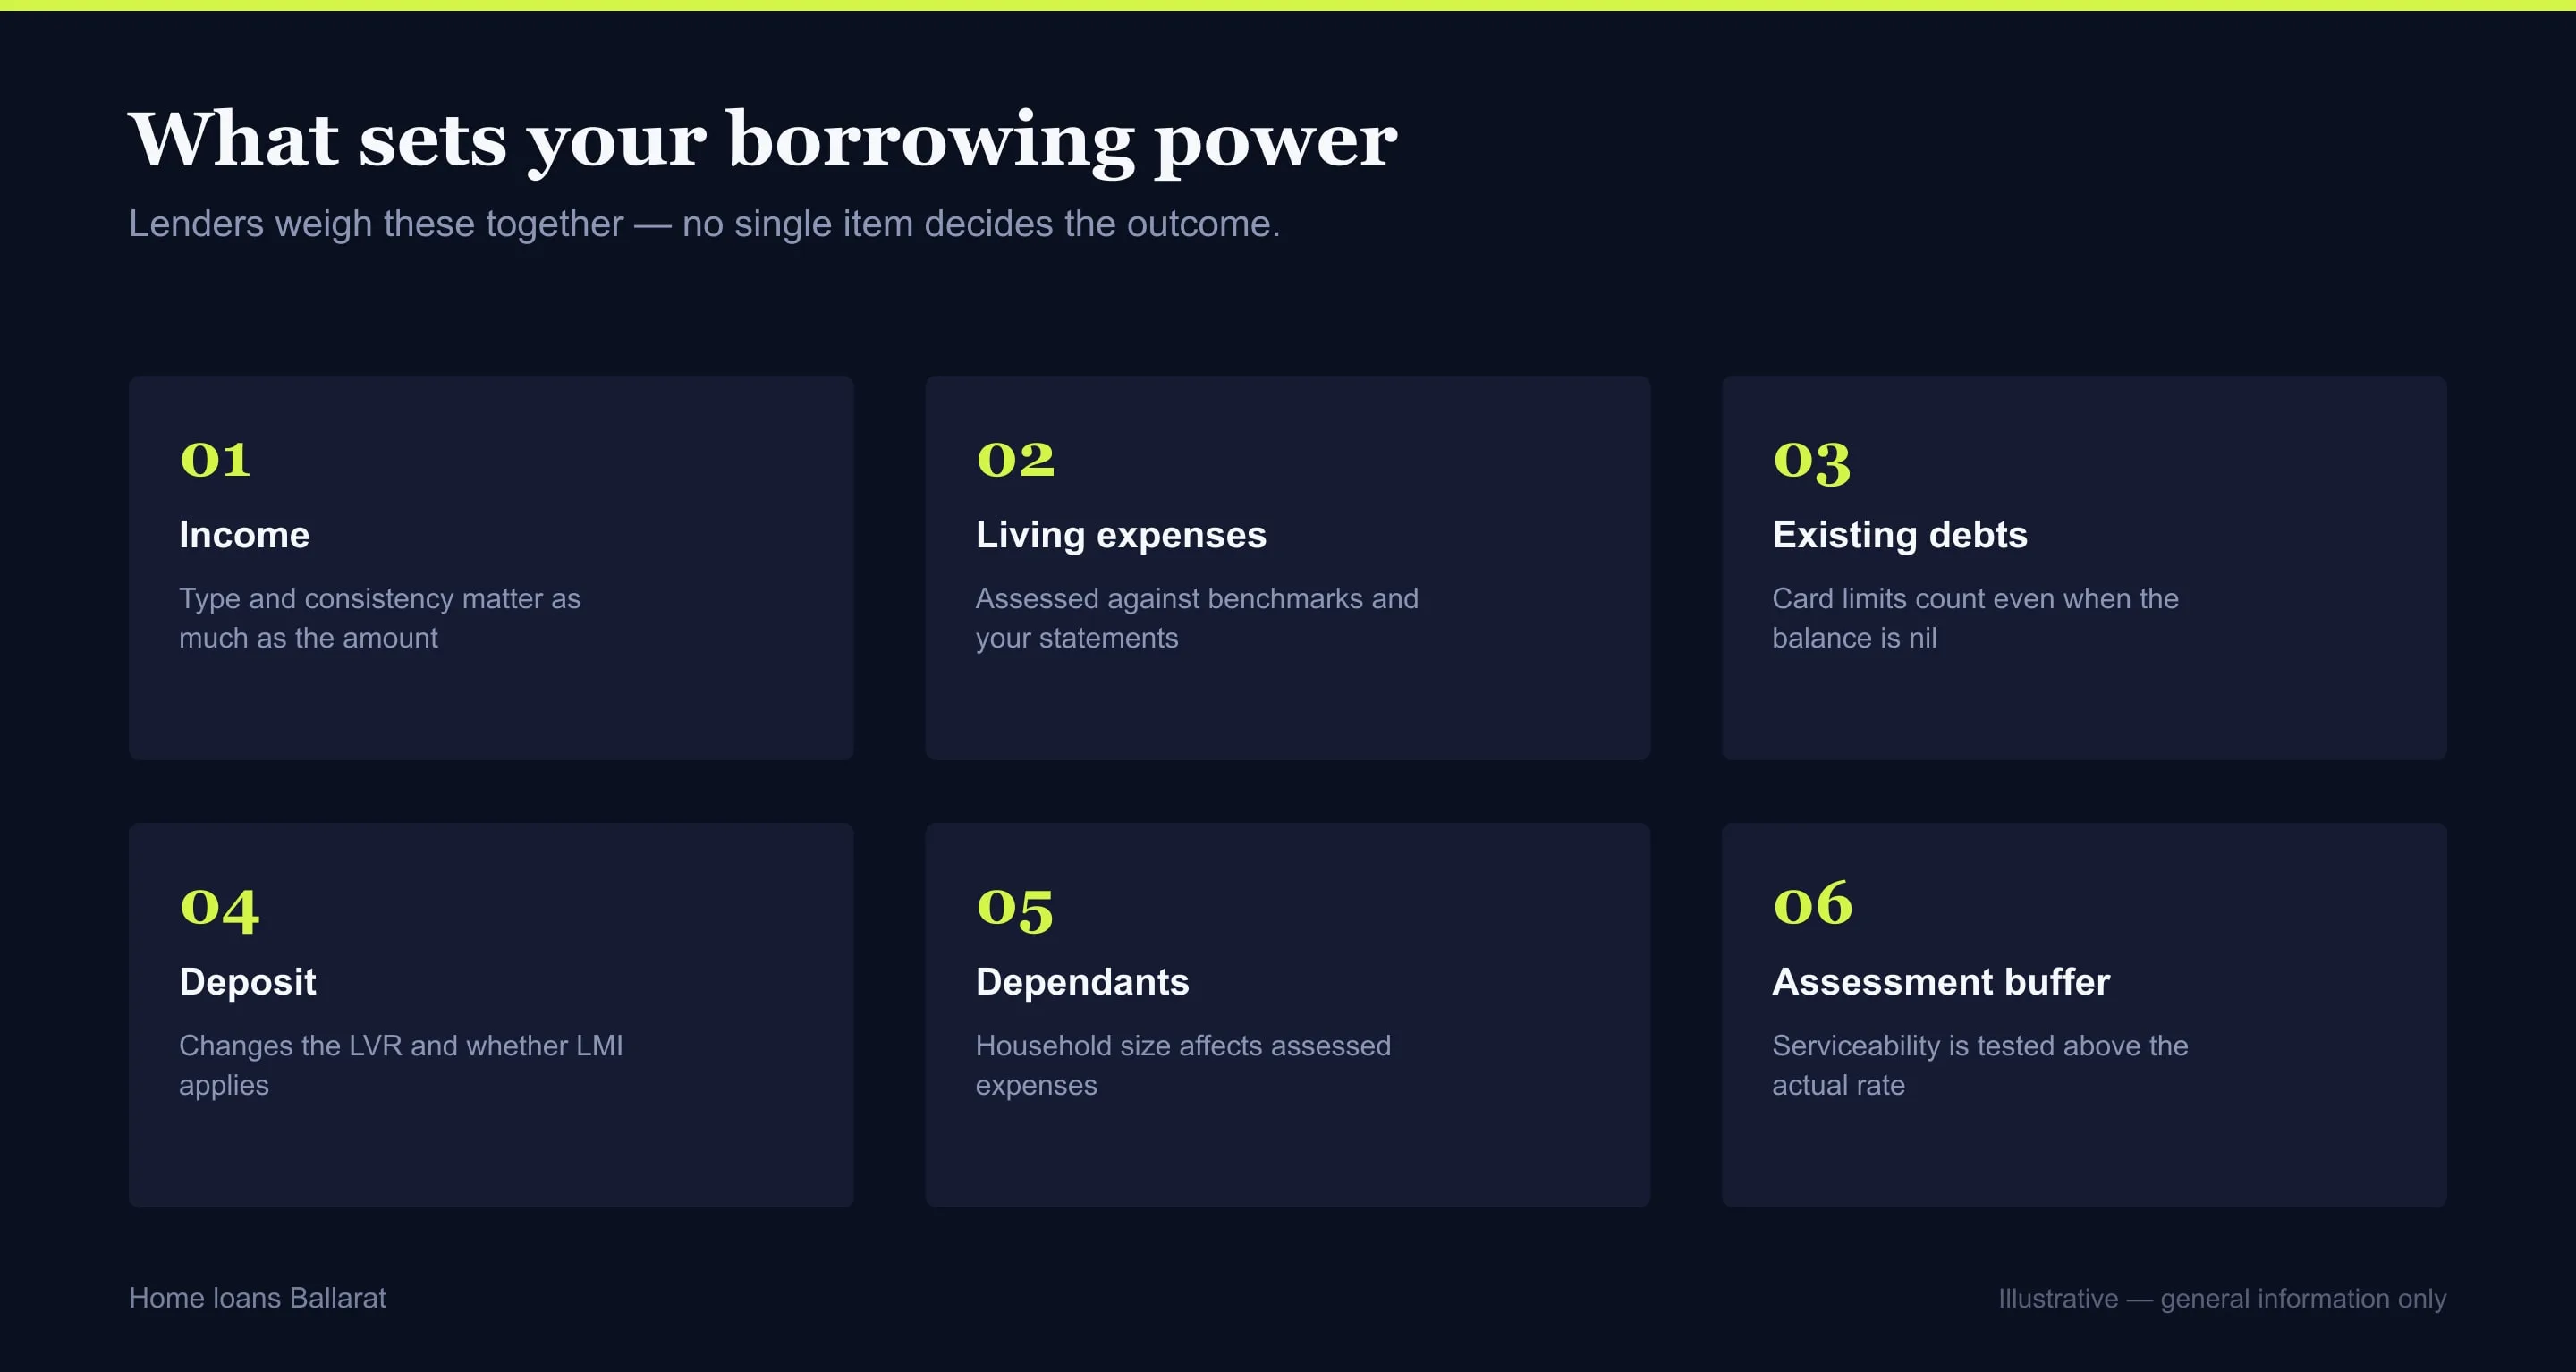
Your borrowing power is one lender's policy applied to your income, debts and deposit. That is why we model it across several lenders rather than one. Four mechanics do most of the work, and none of them are visible from a rate comparison table. They apply to every buyer in Ballarat regardless of which lender you end up with.
- The serviceability buffer. Every lender must assess you at a rate well above the one you will pay, and APRA sets that margin. It applies to new lending and refinances alike, so we build it into the figure we give you rather than quoting a number the assessor will not honour.
- Credit card limits, not balances. An unused card with a $20,000 limit is assessed against you as though you had drawn the full limit. We check your limits early, because closing cards you do not use is usually the quickest lift to your borrowing power we can find.
- The expense benchmark. Lenders compare your declared living costs against the Household Expenditure Measure and assess on whichever figure is higher, so understating your spending gains you nothing. We would rather work from your real numbers and pick a lender who reads them well.
- Deposit against the 80% line. Borrow more than 80% of the property value and Lenders Mortgage Insurance applies. It protects the lender, you pay for it, and it is usually capitalised onto your loan rather than paid upfront. We show you where you sit against that line before you commit to a price.
Choosing How Your Loan Is Structured
Beyond the lender itself, three structural choices shape what your loan costs and how it behaves. We settle these with you before the application goes in, because they are far harder to unwind after approval.
Fixing your rate buys certainty and costs you flexibility. Breaking a fixed loan early carries a cost you cannot predict at the outset. A variable rate moves with the market but generally lets you make extra repayments and hold an offset account. We often split the balance between the two where you want some certainty without locking the whole loan, and we will tell you which side of that split your situation argues for.
An offset account reduces the balance your interest is calculated on while leaving your money available to you. A redraw facility lets you pull back extra repayments you have already made. They reach similar places by different mechanisms, lenders treat them differently, and we check which one your shortlisted lenders actually offer before you choose on the strength of the brochure.
Home Loans Ballarat Buyers Get Assessed For
Lender appetite varies by employment type, property type and location, so we pick the lender around you rather than sending the same file everywhere. A salaried buyer in Wendouree, a sole trader in Sebastopol and an investor buying in Delacombe are three different applications, and the lender who suits one routinely declines another.
The affordability gap with Melbourne works in your favour here, and we use it to widen the lenders worth approaching. REIV put the local median house price at $610,000 in Q2 2026; PRD reported $593,250 for Q4 2025, and InvestorKit had it near $525,000 in early 2026. We quote you the source and the quarter rather than one figure, because the same income supports a larger share of this market than it does in the capital and more properties here sit under the federal scheme caps.
Because we hold accreditation across a panel, we can see where your file will be assessed favourably before you apply. That matters to you directly: every application leaves a credit enquiry behind, and a cluster of them reads badly to the next assessor.
Property type matters as much as postcode. A weatherboard, a townhouse and a unit near the CBD are valued and risk-weighted differently, and a lender comfortable with one can apply a tighter loan-to-value ratio to another. So we check the security as well as your income before we choose where your file goes.
Should You Come to Us, or Go Straight to a Bank?
We will tell you when you do not need us. A bank can only offer its own products under its own policy. If you fit that policy cleanly and you are happy with the terms, going direct is perfectly reasonable. We would rather say so than lodge an application you did not need. Not every enquiry we take in Ballarat turns into a loan we write, and that is fine.
Come to us when your situation is not standard, when you have been declined before, or when you do not know which lenders would read your income favourably. We are also bound by Best Interests Duty, which legally requires us to act in your interests rather than the lender's. The staff selling you a bank's own products do not carry that obligation.
Home Loans Questions
How much can I borrow?
Your income, existing debts, credit card limits, dependants and the lender decide it. The same income produces materially different answers across lenders, because each applies its own policy on top of the regulatory buffer. We model it across several lenders before you apply, so you get a range you can act on rather than a single optimistic number.
What is the serviceability buffer?
Lenders must assess your ability to repay at a rate 3 percentage points above the rate you would actually pay. APRA confirmed the buffer stays at 3 percentage points on 23 July 2025. Whatever rate you are offered, we work your capacity out three points above it, which is why the figure we give you is lower than an online calculator suggests.
Does applying to several lenders hurt my chances?
It can. Each application usually leaves a credit enquiry on your file, and a cluster of enquiries in a short period reads poorly to the next assessor. We identify the right lender first rather than applying broadly and hoping, which is most of what protects your file.
Who You Get When You Call
The person who picks up is the one who runs your borrowing figure and then keeps your file to settlement. Not a call centre passing you to an assessment team. The same person who tells you what you can borrow is the one who argues your case with the lender when the assessor comes back with questions.
That continuity matters most on the parts of a home loan that go wrong quietly. A valuation that lands short, a card limit nobody mentioned, an assessor reading your overtime differently from the last one. We already know your file, so none of those start from the beginning.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
We cover Ballarat and the surrounding shires. Call us and we will work out what you can borrow.