Ballarat, VIC 3350
Rural & Acreage Home Loans Ballarat
Whether a block is fundable is a question about the block, not about you. We answer it from the listing and the planning certificate, at no cost, and we would rather answer it while you can still walk away.
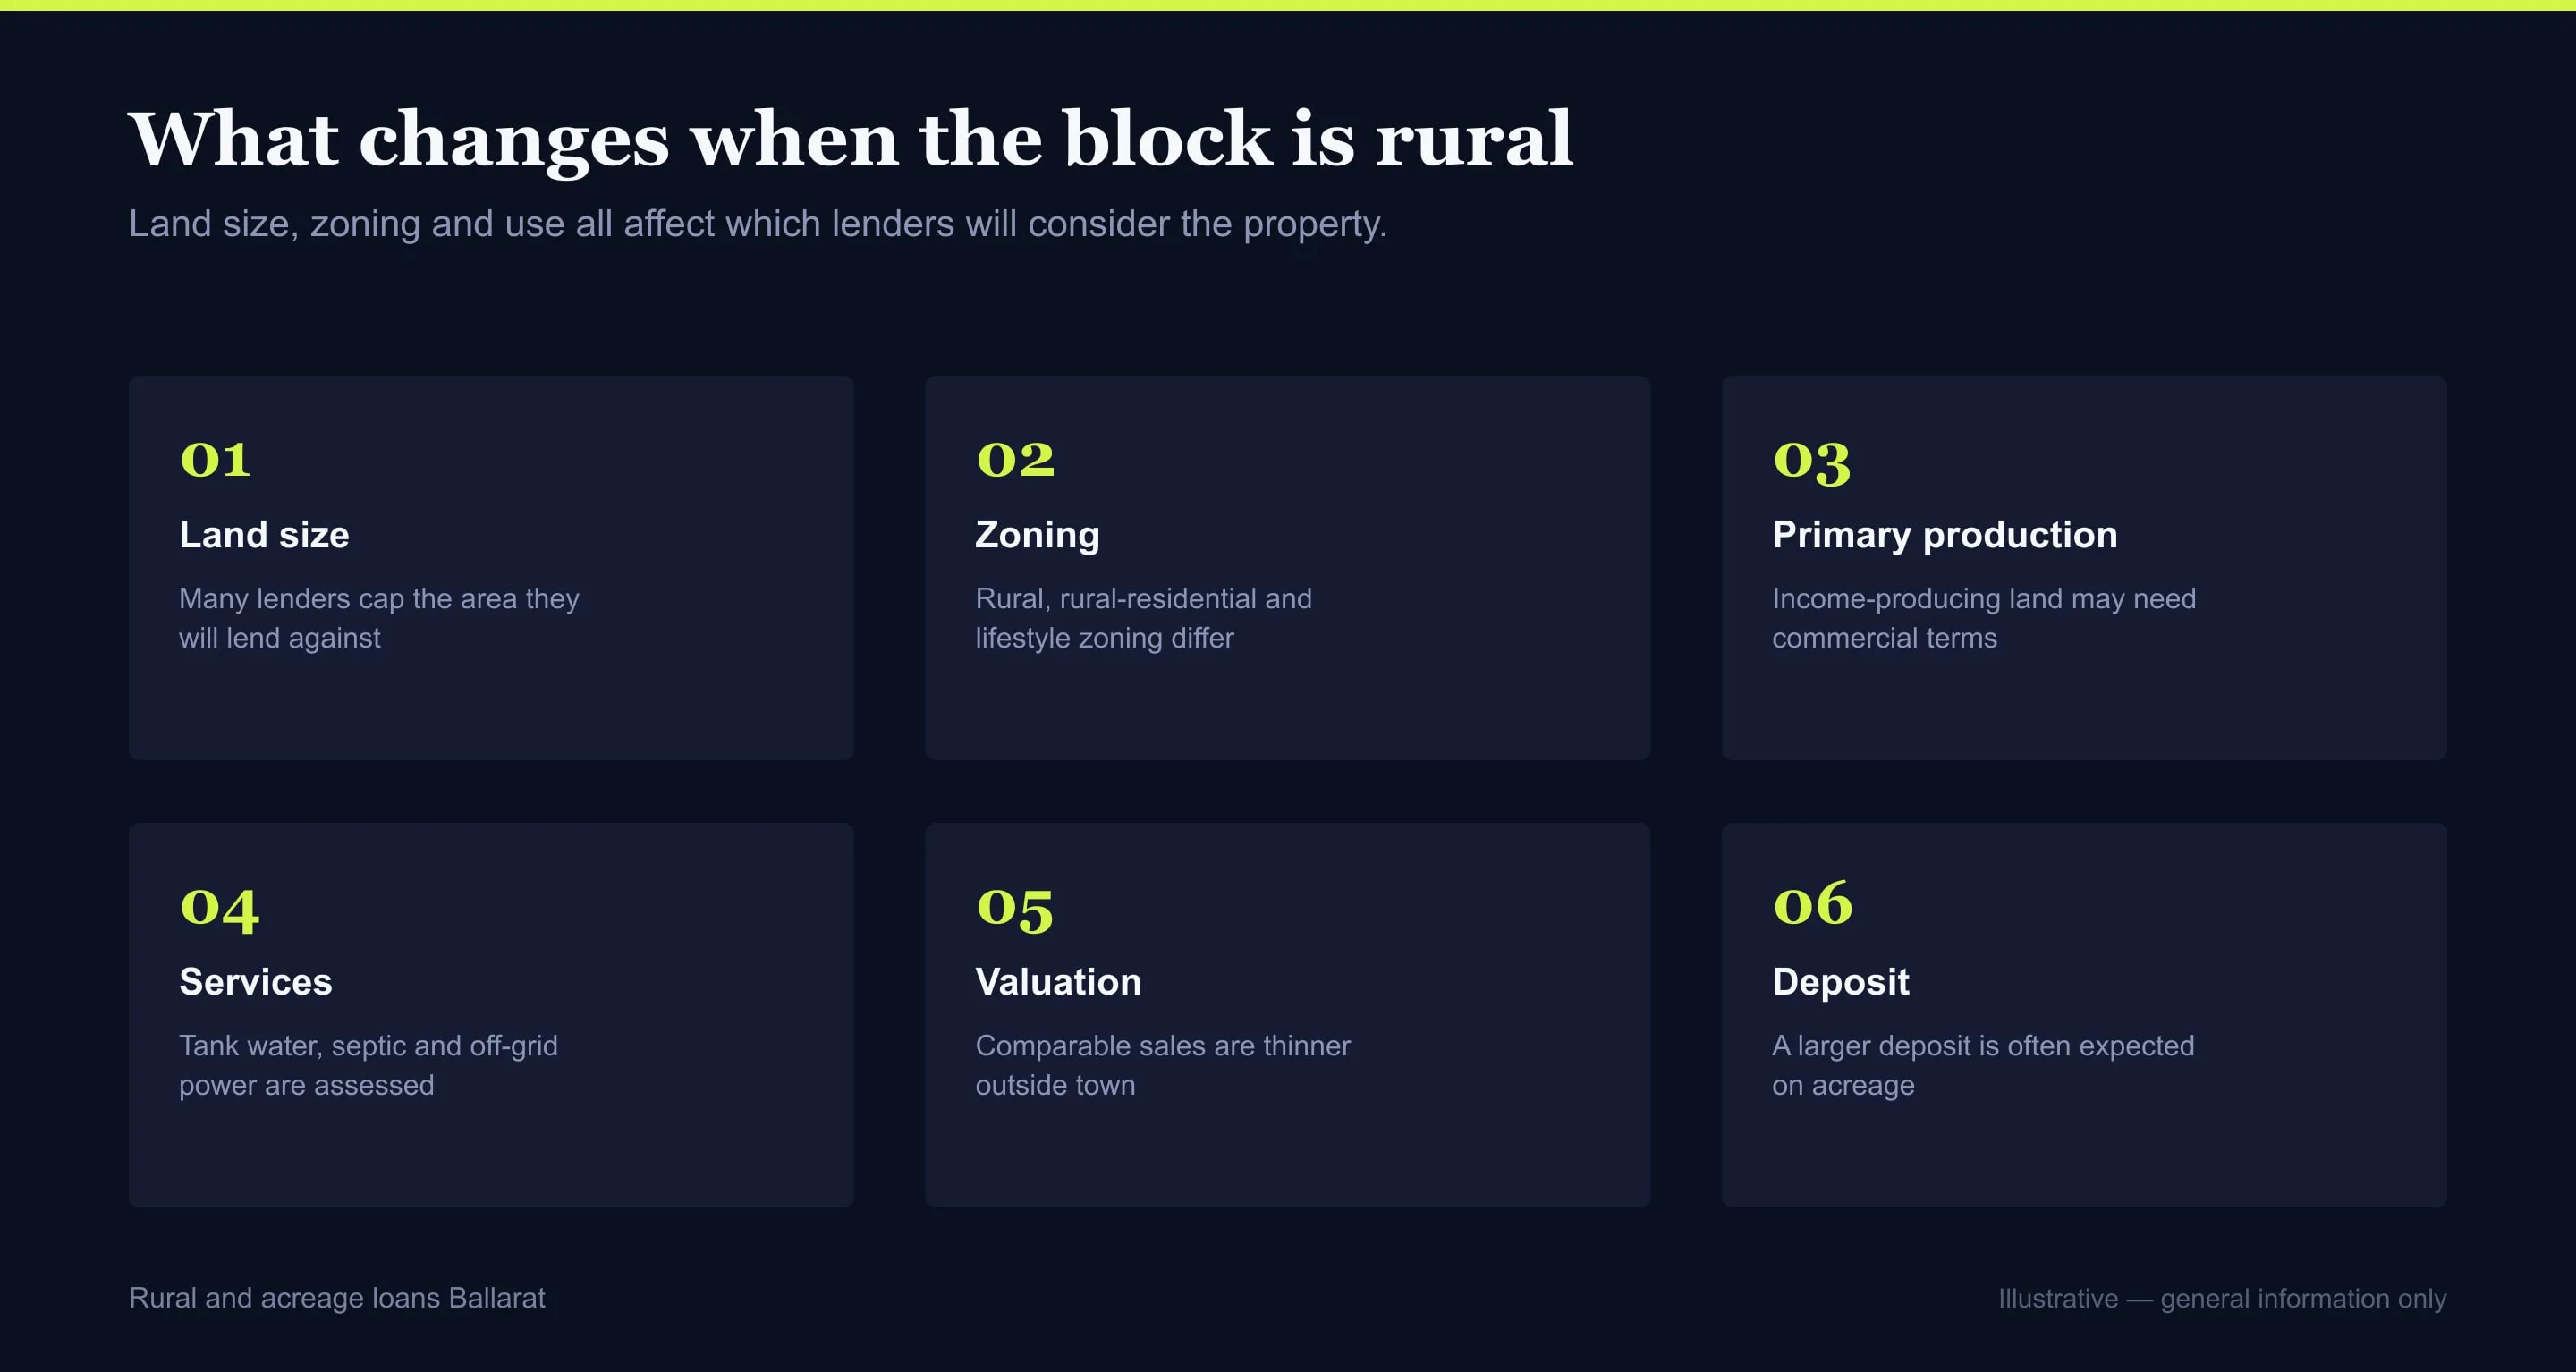
Land size is what decides an acreage file, not the price. Push past about ten hectares and most mainstream lenders step back, and your deposit requirement can change overnight. Zoning and water supply do the same job in a quieter way. We check all three before you make an offer.
What We Do on an Acreage Purchase
We work out whether a mainstream lender will treat your property as an ordinary home loan or whether it needs a specialist product with a larger deposit. That single question is what an acreage file turns on. Lifestyle properties sit in an awkward middle ground: they are not standard residential security but they are not farms either, and every lender draws the line somewhere different.
The shires around Ballarat are full of this stock and we look at it constantly. You can get acreage inside a commute without leaving the region, which is why most of the enquiries we take on land start close to home rather than out west.
Because the property decides as much as your income does, we would rather you sent us a listing than a payslip first. We can tell you within a call whether the block is fundable and on what terms, and that is far cheaper than finding out after you have signed.
What It Costs You to Have a Property Checked
Nothing, and that holds for every block you ask about rather than just the first. There is no call-out fee anywhere in Ballarat or the surrounding shires, and no charge for the ones you end up not buying.
The lender pays us a commission only when a loan settles, and we disclose what we are paid in writing in the Credit Guide before you apply. That covers every lender we might recommend, so you see the arrangement before you are committed to anything.
Two costs on an acreage purchase are yours rather than ours, and we flag them early: the lender's valuation, which can be charged on specialist rural lending, and building insurance where a Bushfire Management Overlay applies. We will tell you to price the insurance before you sign, because it can decide whether the loan is possible at all.
How We Check a Property Before You Offer
Out here the property decides as much as you do, so the checking happens before the offer rather than after it. There is no cost, and you can stop at any point.
-
01
We establish the land size and the zone
We take both from the listing and the planning certificate. Together they decide which lenders we can approach at all, and therefore what deposit you actually need to have ready.
-
02
We check the services and the access
Water supply, wastewater, road frontage and any right-of-way over a neighbouring title. Lenders want a reliable potable supply and a permitted septic system, and difficult access affects both the valuation and the appetite. We place you with a lender who is comfortable with what the property has.
-
03
We have you price the insurance early
Where a Bushfire Management Overlay applies, we ask for a quote before you sign anything. Lenders require cover in place at settlement, so insurance you cannot obtain stops the loan regardless of how good your file is.
-
04
We allow for a slower valuation
Comparable sales are sparser and valuers have to travel out from Ballarat, so we build a realistic timeline into the finance clause rather than letting you sign to a suburban one and then chase an extension.
What We Need From You
- The listing, with the land size in hectares or acres
- The section 32 or planning certificate, showing the zone and any overlay
- What the water supply is, whether mains, tank, bore or dam, and where the wastewater goes
- How the property is accessed, and whether the road is sealed
- Your income documents and your deposit position
Talk Through Rural & Acreage Home Loans Ballarat
Tell us which property you are looking at and we will work out which lenders can fund it, what deposit you will need, and what to expect from the valuation. Call us before you make an offer.
Related Lending
Before You Call
What do you need from me to check a property?
The listing and the section 32 are the two things that matter most, plus a rough idea of your income and deposit. That is enough for us to tell you whether it is fundable, which lenders would look at it, and what deposit to budget for.
What happens if no lender will fund the property?
We tell you before you offer, and we tell you what would change it: a smaller holding, a different zone, or a larger deposit that opens the specialist panel. We would much rather deliver that news while you are still looking than while you are trying to satisfy a finance clause.
How many properties will you check for me?
As many as you need, and we do not charge for any of them. Checking properties is how we end up arranging the loan on the one you buy.
Will you come out to the property?
We can, anywhere in Ballarat and the surrounding shires, at no charge. In practice the listing, the section 32 and the planning certificate tell us more than a site visit would, so most of this work happens before anyone drives anywhere.
How Much Land We Can Fund Normally
Land area is the first filter we apply, and knowing the thresholds before you fall for a listing is most of what saves people trouble here.
Many mainstream lenders treat properties up to around two hectares as standard residential security and lend on ordinary terms, which is where we place you if the block allows. Between roughly two and ten hectares a number of lenders will still lend but often at a reduced loan-to-value ratio, so we recalculate your deposit against that rather than against the price.
Beyond about ten hectares most mainstream lenders step back and your purchase moves into rural or specialist lending, which means larger deposits, different pricing and a considerably narrower panel. We will tell you which side of that line you are on before you offer, because it can change your deposit requirement by tens of thousands. A good deal of the acreage listed within half an hour of Ballarat sits in exactly that middle band.
Those figures are indicative rather than universal. Individual lenders set their own limits and apply their own overlays, and a property one lender declines outright is routine business for another. That is exactly why we confirm the specific lender's policy against your specific property rather than working off a threshold.
What We Check on the Property Itself
Beyond size, three characteristics decide how straightforward your lending will be, and we look at all three off the listing and the section 32 before we approach anyone.
Zoning is the most consequential thing we check. Farming Zone, Rural Living Zone and Rural Conservation Zone are read differently, and a property zoned for agriculture is assessed on a different basis from one zoned rural residential even where the actual use is identical. The zone is on the planning certificate, and we would rather read it before you bid than explain it to a lender after you have signed.
Water supply matters because many acreage properties have no reticulated mains connection. Tank water, a bore or a dam is normal outside Ballarat and most lenders accept it, provided a reliable potable supply exists and your wastewater system is permitted and functional. We ask what the arrangements are early and match you to a lender comfortable with them.
Access is the third. Sealed road frontage is straightforward; a property reached only by an unsealed road, a right-of-way over a neighbouring title, or a crossing that floods in wet weather can affect both the valuation and the lender's appetite, and we would rather raise it with you than let it surface in a valuer's report.
One further point we always raise: much of the acreage around Ballarat carries a Bushfire Management Overlay, which affects insurance availability and cost. Lenders require insurance in place at settlement, so where cover is hard to obtain the loan is hard too. We have you get a quote before you commit rather than after.
Rural Acreage Home Loans Ballarat District Buyers Need
The sequence for an acreage purchase differs from a suburban one, and getting it in the right order is where we save you the most trouble.
We establish the land size and the zone from the listing and the planning certificate first, because together they decide which lenders can be approached at all and therefore what deposit you actually need. If you have budgeted for a 10% deposit and the property requires 30%, we want you to know that before a contract is signed rather than while you are trying to satisfy a finance clause.
Valuations out here also take longer and come back less predictably than they do in Ballarat itself. Comparable sales are sparser, valuers travel further, and the range of outcomes is wider. We build that into the finance clause we recommend to your conveyancer rather than letting you sign to a suburban timeline that the valuation cannot meet.
Where you are buying changes the shape of all this. A rural residential block on the fringe of Ballarat generally sits inside standard residential policy and behaves like a suburban file; a comparable holding further out in Pyrenees or Golden Plains routinely does not. We work out which of those your property is before we approach anyone, because the answer sets your deposit.
Should You Buy Acreage, or a Large Suburban Block?
Acreage buys you space, privacy and the option to keep animals or grow something. What it costs you on the finance side is a narrower lender panel, potentially a much larger deposit, slower valuations, and ongoing considerations like tank water, septic maintenance and bushfire insurance. We will quantify all of that for you before you decide.
A large block on the edge of Ballarat itself gets you room without leaving standard residential lending: simpler loan, smaller deposit, faster valuation. If that would suit you, we will say so rather than arranging the harder loan.
If the acreage is the point, that is a perfectly good reason to accept the friction and we will get it done. If it is mainly about space, the suburban option often reaches the same result with far less complexity, and we would rather tell you that early.
Rural & Acreage Home Loans Questions
How much land can I buy with a normal home loan?
More than you would expect, if the lender is chosen for the block. The limits are set by each lender rather than by any rule, and a holding one declines outright is routine business for another. Send us the listing and we will tell you which side of the line yours falls on.
Does zoning affect my loan?
Yes, significantly. Farming Zone, Rural Living Zone and Rural Conservation Zone are assessed differently, and the zone can matter more than how the property is actually used. We read the planning certificate before you make an offer rather than after.
Can I get a loan on a property with tank water?
Usually. Tank water, a bore or a dam is normal on acreage around Ballarat and most lenders accept it, provided a reliable potable supply exists and any wastewater system is permitted and working. We match you to a lender comfortable with your particular arrangement.
Do I need a bigger deposit for acreage?
Often. Larger holdings, restrictive zoning or difficult access commonly mean a reduced loan-to-value ratio, which translates directly into a larger deposit. We establish that figure for you before you sign a contract, not after.
Does a bushfire overlay affect the loan?
Indirectly but importantly. Lenders require insurance at settlement, and a Bushfire Management Overlay can make cover more expensive or harder to obtain. Where it is unavailable the finance generally is too. We have you get an insurance quote early for exactly this reason.
Who Checks the Property
The person you speak to is the one who checks each block you are considering against lender policy: the land size, the zoning, the water supply, the wastewater system and the access. They do that before you offer, not after a valuation comes back.
You will most likely look at several blocks before one is both right and fundable, and we check as many as you need. The point is knowing which side of the mainstream lending line a property sits on while you can still walk away from it.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
Acreage sits in the shires rather than in Ballarat itself, and that is most of what we fund out here. Ring us with a block in mind and we will check it against lender policy.