Ballarat, VIC 3350
Refinancing Ballarat
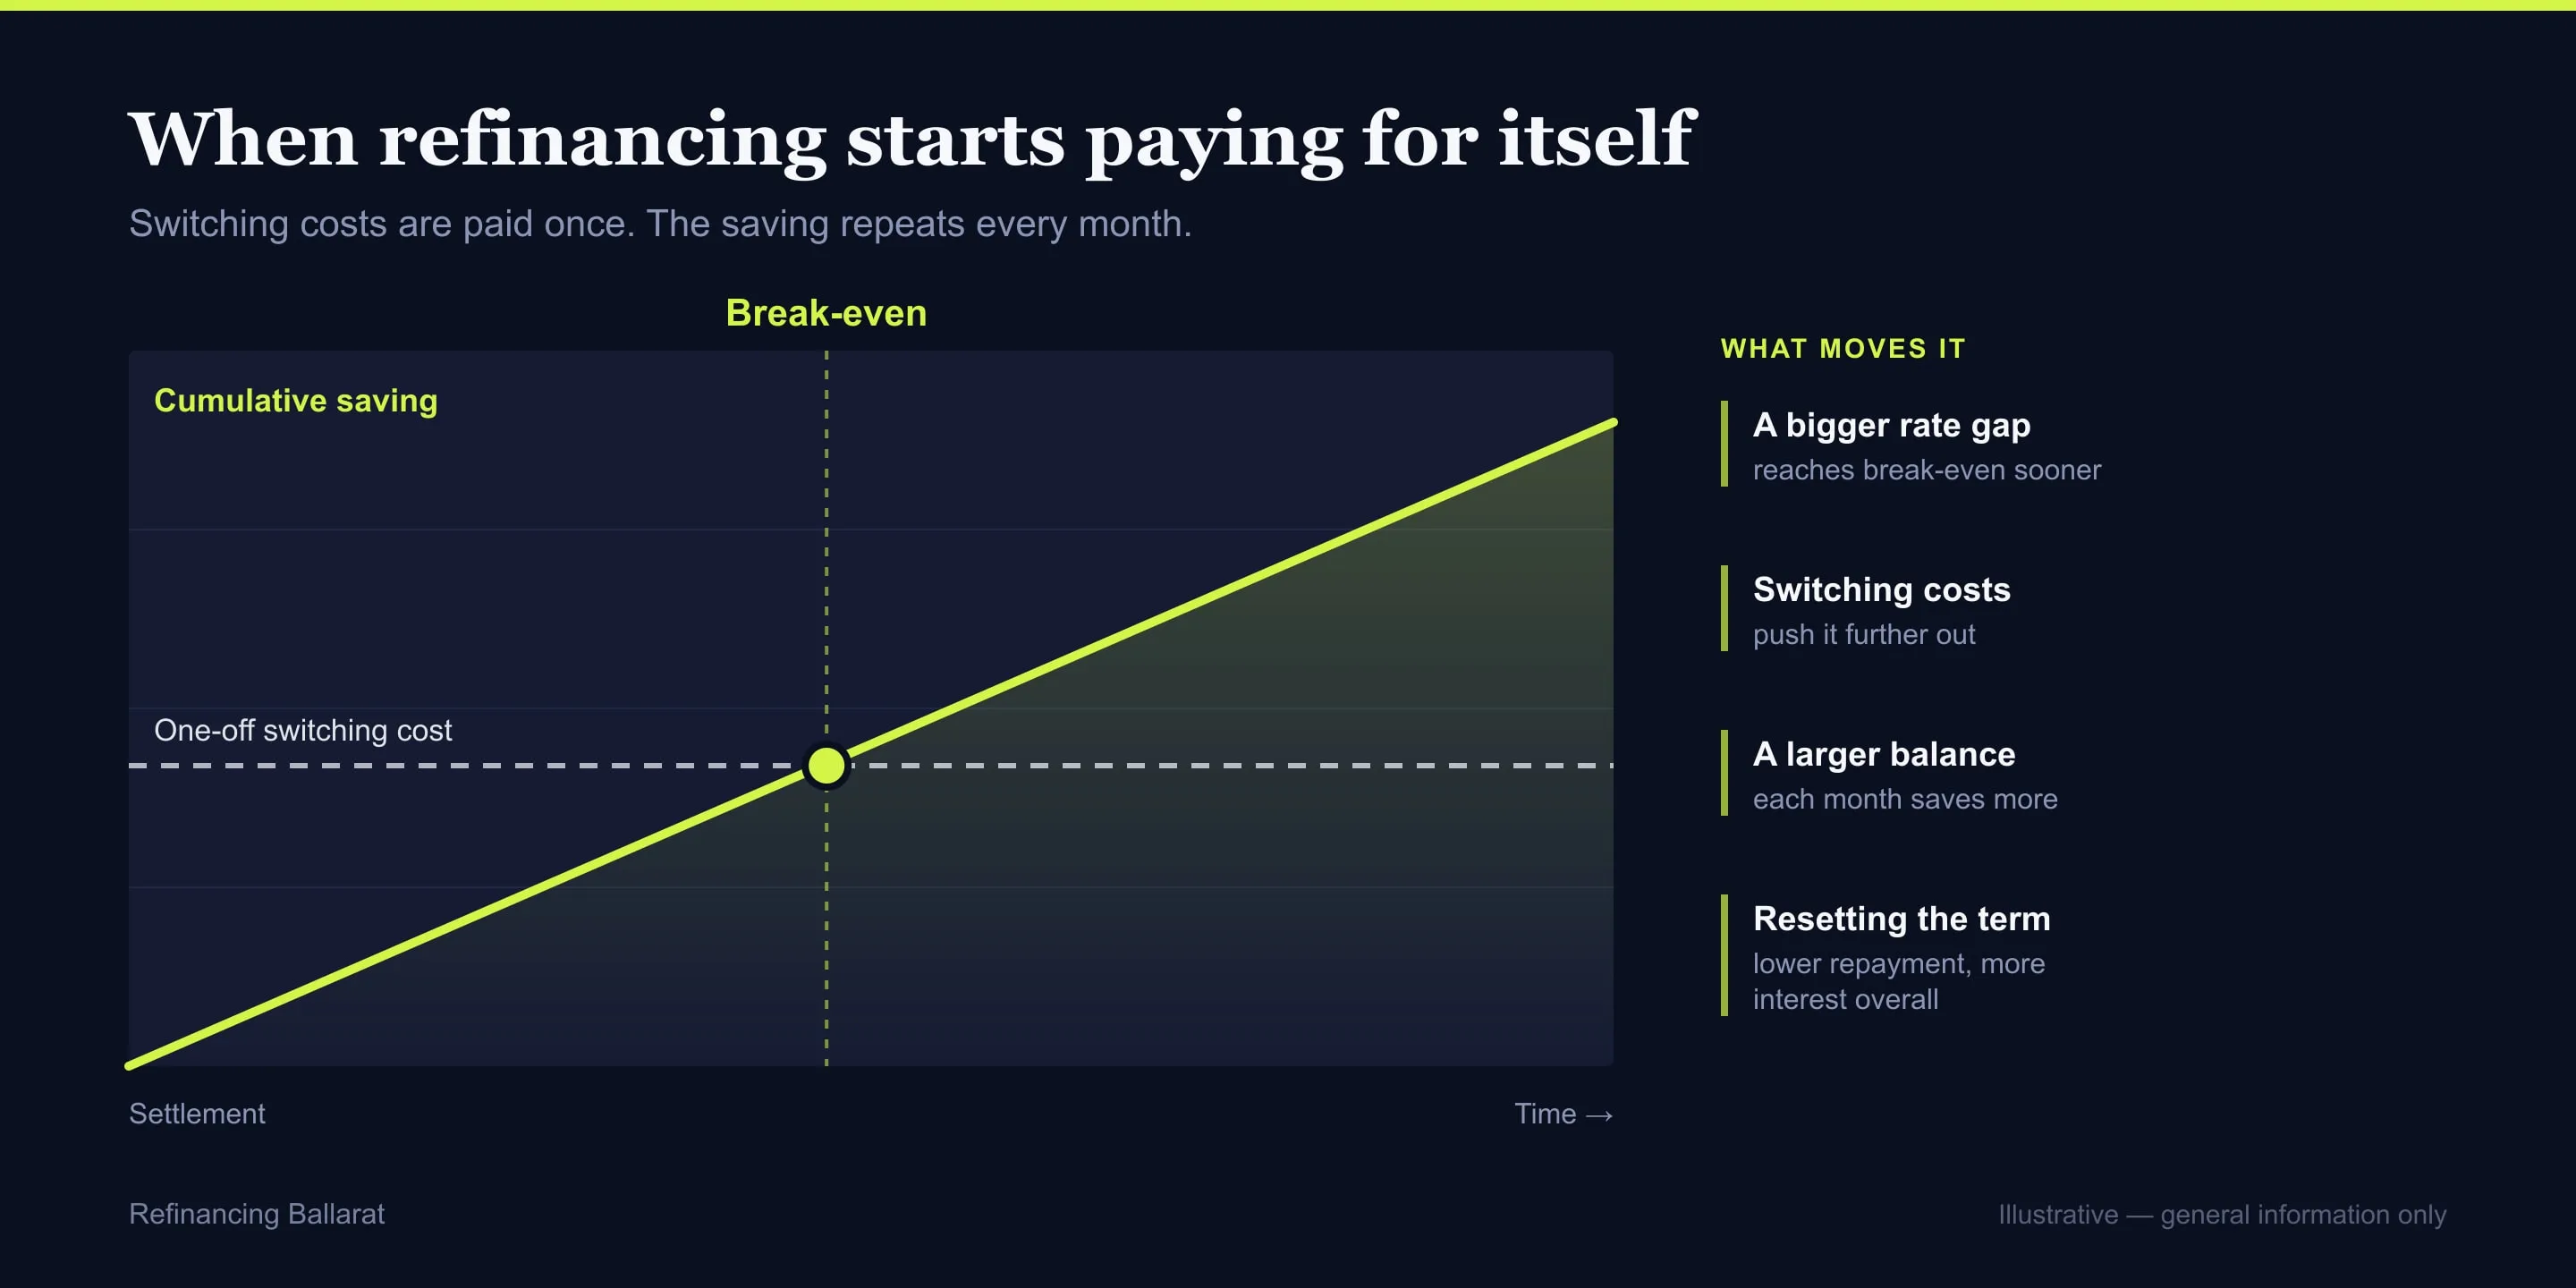
Switching lenders only pays if the saving beats the cost of getting out, and the cost of getting out is the part most people never price. Break fees, discharge charges, a new registration, sometimes a valuation. We total that first and treat it as the hurdle the new loan has to clear.
Equity is the constraint that stops more of these than anything else. If your loan sits above eighty per cent of what the place is now worth, Lenders Mortgage Insurance comes back into play and you may pay it a second time on a loan you already insured. We check that first, before anything else is worth pricing.
What We Do on a Refinance
We replace your existing home loan with a new one, either at a different lender or restructured with the one you already have. It is a full new application. The new lender assesses your income, debts and the property from scratch, then on approval pays out your old loan and takes over the mortgage.
You will have one of three reasons for calling us: you want a better rate, you want to access equity for renovations or another purchase, or you want to restructure by rolling debts in, moving off interest-only, or splitting fixed and variable. We handle all three, and the first thing we do is work out which one you are actually solving for.
Being an existing borrower in good standing does not exempt you from assessment, and this is where refinances surprise people. If your income has dropped, your debts have grown, or your property has not held its value, you can be declined despite never missing a repayment. So we test your position against lender policy before you lodge anything and leave an enquiry behind. We review loans for owners right across Ballarat and the district, and a fair number of those reviews end with us saying stay put.
What It Costs You to Have Us Check
Nothing. We price your current loan, estimate your equity position and tell you whether moving is worth it at no cost to you, and there is no call-out fee anywhere in Ballarat. The lender pays us a commission only if a new loan settles.
That means we get paid when you move, so it matters that we say this plainly: on a good share of the refinances we look at, the answer is stay where you are and ring your lender for a retention rate. We will tell you when that is the better move, and it costs you nothing to have us reach that conclusion.
What we are paid is disclosed to you in writing in the Credit Guide before you apply, covering every lender we might recommend. The exit costs on your existing loan are a separate thing entirely. Those are your current lender's charges, and we set them out for you in the first stage below.
How We Check a Refinance Before You Commit
We do all of this before anything is lodged, because the honest answer is often that moving is not worth it. You can stop at any stage without cost.
-
01
We price what you have now
We take your current rate, any fixed term still running, and what your lender charges to release the mortgage. We treat that total as the hurdle a new loan has to clear for you, and we tell you if it does not.
-
02
We work out where your equity sits
We estimate your loan-to-value ratio before an application goes near a lender, because it decides which lenders will look at you and on what terms. Above 80% the arithmetic usually ends the exercise.
-
03
We give your current lender a chance
If price is the only issue, we have you make a retention call first. It costs you nothing and sometimes settles the matter, and we would rather tell you that than lodge an application you did not need. It is the advice we give Ballarat borrowers most often, and it is the advice we are paid least for.
-
04
We lodge, discharge and settle
We submit the new application for assessment from scratch, serve your outgoing lender with the discharge authority, and settle the two together. Discharges are where refinances stall, so we chase that side rather than assume it.
What We Need From You
- Your current loan statement, showing balance, rate and whether any part is fixed
- A break cost quote from your lender if you are inside a fixed term
- Recent payslips or business financials, and statements for your everyday accounts
- The rates notice and the building insurance certificate for the property
- Details of any other debts you are thinking of rolling in
Talk Through Refinancing Ballarat
Tell us what loan you are on now and we will work out what your exit costs are, where your equity sits against the 80% line, and whether moving is worth it. Call us if you would rather talk it through now. We will tell you plainly if the answer is stay put.
Related Lending
Before You Call
How long does a refinance take?
Commonly a few weeks from lodgement to settlement, though the discharge from your existing lender is the part that most often adds time and it is outside the new lender's control. We chase both sides so the two settle together rather than leaving you carrying the old loan longer than you need to.
What happens if you find it is not worth moving?
We tell you, and we tell you what would change the answer: usually more equity, a lower rate gap closing, or a fixed term running out. There is no charge for reaching that conclusion, and you are welcome to come back when your position has shifted. Plenty of the Ballarat borrowers we speak to end up doing exactly that a year or two later.
Do we have to meet in person?
Only if you want to. We will come to you anywhere in Ballarat and the surrounding shires at no charge, or run the whole refinance by phone and email. A refinance is documents rather than site visits, so it works either way.
Whether Moving Is Worth It for You
It comes down to the gap between what you are paying and what you could pay, weighed against the cost and effort of moving. We price both sides before you decide, rather than selling you the gap alone.
The most common reason to call us is a fixed term ending. Many loans revert to a higher variable rate automatically and the reversion rate is rarely competitive. So we would rather review your loan before that date than after it. That timing is where most of the value sits, and it is easy to miss by a month.
The other prompts are equity-driven and they work in your favour. If your property has gained value your loan-to-value ratio has fallen, which can qualify you for pricing that was not available when you first borrowed, so we re-estimate your LVR rather than assuming the number you had at purchase. Releasing equity for a renovation or a deposit on an investment property is a refinance too, and we treat it as new lending because that is how the lender will.
Where you sit in Ballarat changes how well that works. If you bought in an established suburb several years ago, growth has usually done the work for you and the refinance is straightforward. If you bought recently in one of the growth estates, we will often find the equity is not there yet. We would rather tell you that in a phone call than after you have paid for a valuation.
Renovation drives a lot of what we see in the older parts of Ballarat, where much of the housing stock is Victorian or Edwardian and improving what you have often beats moving. We fund that work by releasing equity like any other refinance. We assess your current position rather than the one you had when you bought, and that is usually better than you expect if you have been in the house a while.
What Leaving Your Current Lender Costs
Switching is not free, and the exit costs are the part you are most likely to underestimate. We total them up front and treat that figure as the hurdle any new loan has to clear.
If you are inside a fixed term, break costs apply. Your lender calculates them from the movement in wholesale funding rates since you fixed, so they can be substantial or close to nothing depending on which way rates have moved. Nobody can tell you your figure without asking, because it is specific to your loan, balance and remaining term. We have you request a written quote from your lender before we go any further.
Beyond break costs you face a discharge fee from your outgoing lender, mortgage registration and discharge fees payable to Land Use Victoria, and sometimes an application or valuation fee at the new lender. Some lenders offset these with a switching incentive, and we check whether the incentive actually covers your real cost rather than letting you assume it does. None of those charges vary because you are in Ballarat rather than Melbourne, so the hurdle is the same either way.
The Equity Trap Facing Recent Ballarat Buyers
The constraint that stops most refinances is your loan-to-value ratio, and it bites hardest if you bought recently. So we estimate it before an application goes anywhere near a lender.
If you bought in Ballarat in the last few years with a small deposit, you are the most exposed to this. Your equity builds from two sources, repayments and price growth, and neither has had long to work.
Lenders Mortgage Insurance is not refundable and it does not transfer between lenders, so if you paid LMI on your original purchase and refinance while still above 80% you pay it a second time, on the new loan, from scratch. That cost frequently exceeds the interest saving you were refinancing for, so we work out where you sit against the 80% line before anything else.
This is why your equity position matters more than the rate comparison you have been reading. Below 80% we can generally move you without difficulty. Above it the arithmetic changes completely, and we will often tell you to wait rather than spend the exit costs to end up worse off.
The serviceability buffer applies to refinances as well as new lending, which produces the situation known as mortgage prison: you comfortably service your existing loan but cannot pass assessment on an identical loan at a cheaper rate, because the assessment rate sits above the rate you are actually paying. Lender policy on this varies more than on almost anything else, so we check your file across the panel. Some lenders take a markedly more accommodating view of like-for-like refinances than others.
Should You Move, or Should We Get Your Lender to Match?
Before we put you through a full application elsewhere, we will usually have you ask your existing lender to review your rate. Retention pricing exists and lenders would rather discount than lose your loan. It costs you nothing, takes a phone call, and sometimes ends the exercise there.
We will recommend actually moving when the gap is wide, when you want features your current lender does not offer, or when you need to restructure in a way they will not accommodate. If price is the only issue and your lender matches it, staying avoids every exit cost above and we will say so.
Refinancing Questions
How often can I refinance?
There is no legal limit. In practice, refinancing repeatedly in a short period leaves a trail of credit enquiries that later assessors notice, and the switching costs accumulate. We would generally have you review every few years or when your circumstances change, rather than chasing every rate movement.
Will refinancing hurt my credit score?
A single refinance application creates one credit enquiry, which has a modest effect. Several applications in a short window has a larger one. We identify the right lender first rather than applying to several, which avoids most of the damage.
What are break costs?
A charge for exiting a fixed-rate loan early, calculated by your lender from the movement in wholesale funding rates since you fixed. The amount is specific to your loan, so we have you get a written quote from your lender before we make any recommendation.
Can I refinance if my property has fallen in value?
Possibly, but a lower valuation raises your loan-to-value ratio, which can push you above 80% and trigger Lenders Mortgage Insurance on the new loan. Where the fall is significant we may not be able to move you at all until equity rebuilds, and we will tell you that before you spend anything. We use recent Ballarat sales rather than the price you paid when we estimate where you stand.
Can I refinance to a lower rate if I am on a low income?
You still have to pass serviceability at the assessment rate, not the rate you would pay. This is the mortgage prison problem. Lender policy differs here, and checking your file across a panel is the main thing we can do that you cannot do yourself.
Who Prices Your Switch
The person who answers is the one who totals your exit costs and works out whether moving actually pays. That includes asking your current lender for a written break cost quote and reading the number back to you against what the new loan would save.
A fair share of those conversations end with us saying stay put. We would rather tell you that on the phone than after you have paid for a valuation, and we will tell you what would need to change before it is worth asking again.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
We look at existing loans right across the Ballarat district. The exit costs and your equity position are what decide it, and both can be worked out on the phone.