Ballarat, VIC 3350
Construction Loans Ballarat
A construction loan does not land in your account. It releases in stages, pays your builder directly as each one is inspected, and charges you interest only on what has been drawn so far. That is a different loan from the one that buys an existing house, and it wants a lender chosen for it.
Most of what goes wrong on a build goes wrong before the slab, in the contract and the paperwork behind it. We read both before anything is lodged, because a file assembled properly at the start is a file where each stage releases on time.
What We Do on a Build
We fund your build rather than a purchase, which means arranging a loan that releases in instalments tied to construction milestones and pays your builder directly as each stage is completed and inspected, rather than one lump sum at settlement. That structure is the main reason a build needs a lender chosen for it rather than whoever offered you the cheapest purchase rate.
Most builds we do in Ballarat are house-and-land: you settle on the land first using a land loan or the land portion of the construction facility, then the build component draws down as work proceeds. We set both halves up together, because a land settlement arranged without the build in view is the most common way people end up stuck with a block they cannot fund a house on.
Your loan converts to an ordinary home loan at practical completion, at which point full principal-and-interest repayments begin on the whole balance. We tell you what that repayment will be at the outset, since it is the number your budget actually has to survive.
What It Costs You to Talk to Us
Nothing. We will read your building contract, check the plans and tell you whether the finance stacks up before you sign anything, at no cost to you and with no call-out fee anywhere in Ballarat or the district. The lender pays us a commission only when your loan settles.
What we are paid is set out in writing in the Credit Guide we give you before you apply, covering every lender we might recommend. You will see it before you are committed to anything.
We are not building consultants and we will not price your build for you. The builder does that. What we do is tell you whether a lender will fund the contract in front of you, and what it will cost you to carry the build while it runs.
How We Get Your Build Funded
We build the loan around your building contract, so we want to see the contract and the plans before anything is lodged. You can stop at any stage without cost.
-
01
We size the loan against the finished build
We have the lender value the property as if complete, meaning land plus build, and lend against that figure. We measure your deposit against the combined number rather than the land price, so you know your real position from the outset.
-
02
We get your builder's paperwork in order
The signed fixed-price contract, council-approved plans and specifications, the builder's registration and their domestic building insurance certificate. We chase the gaps here before lodgement, because this is where builds stall.
-
03
We settle the land, then run the draws
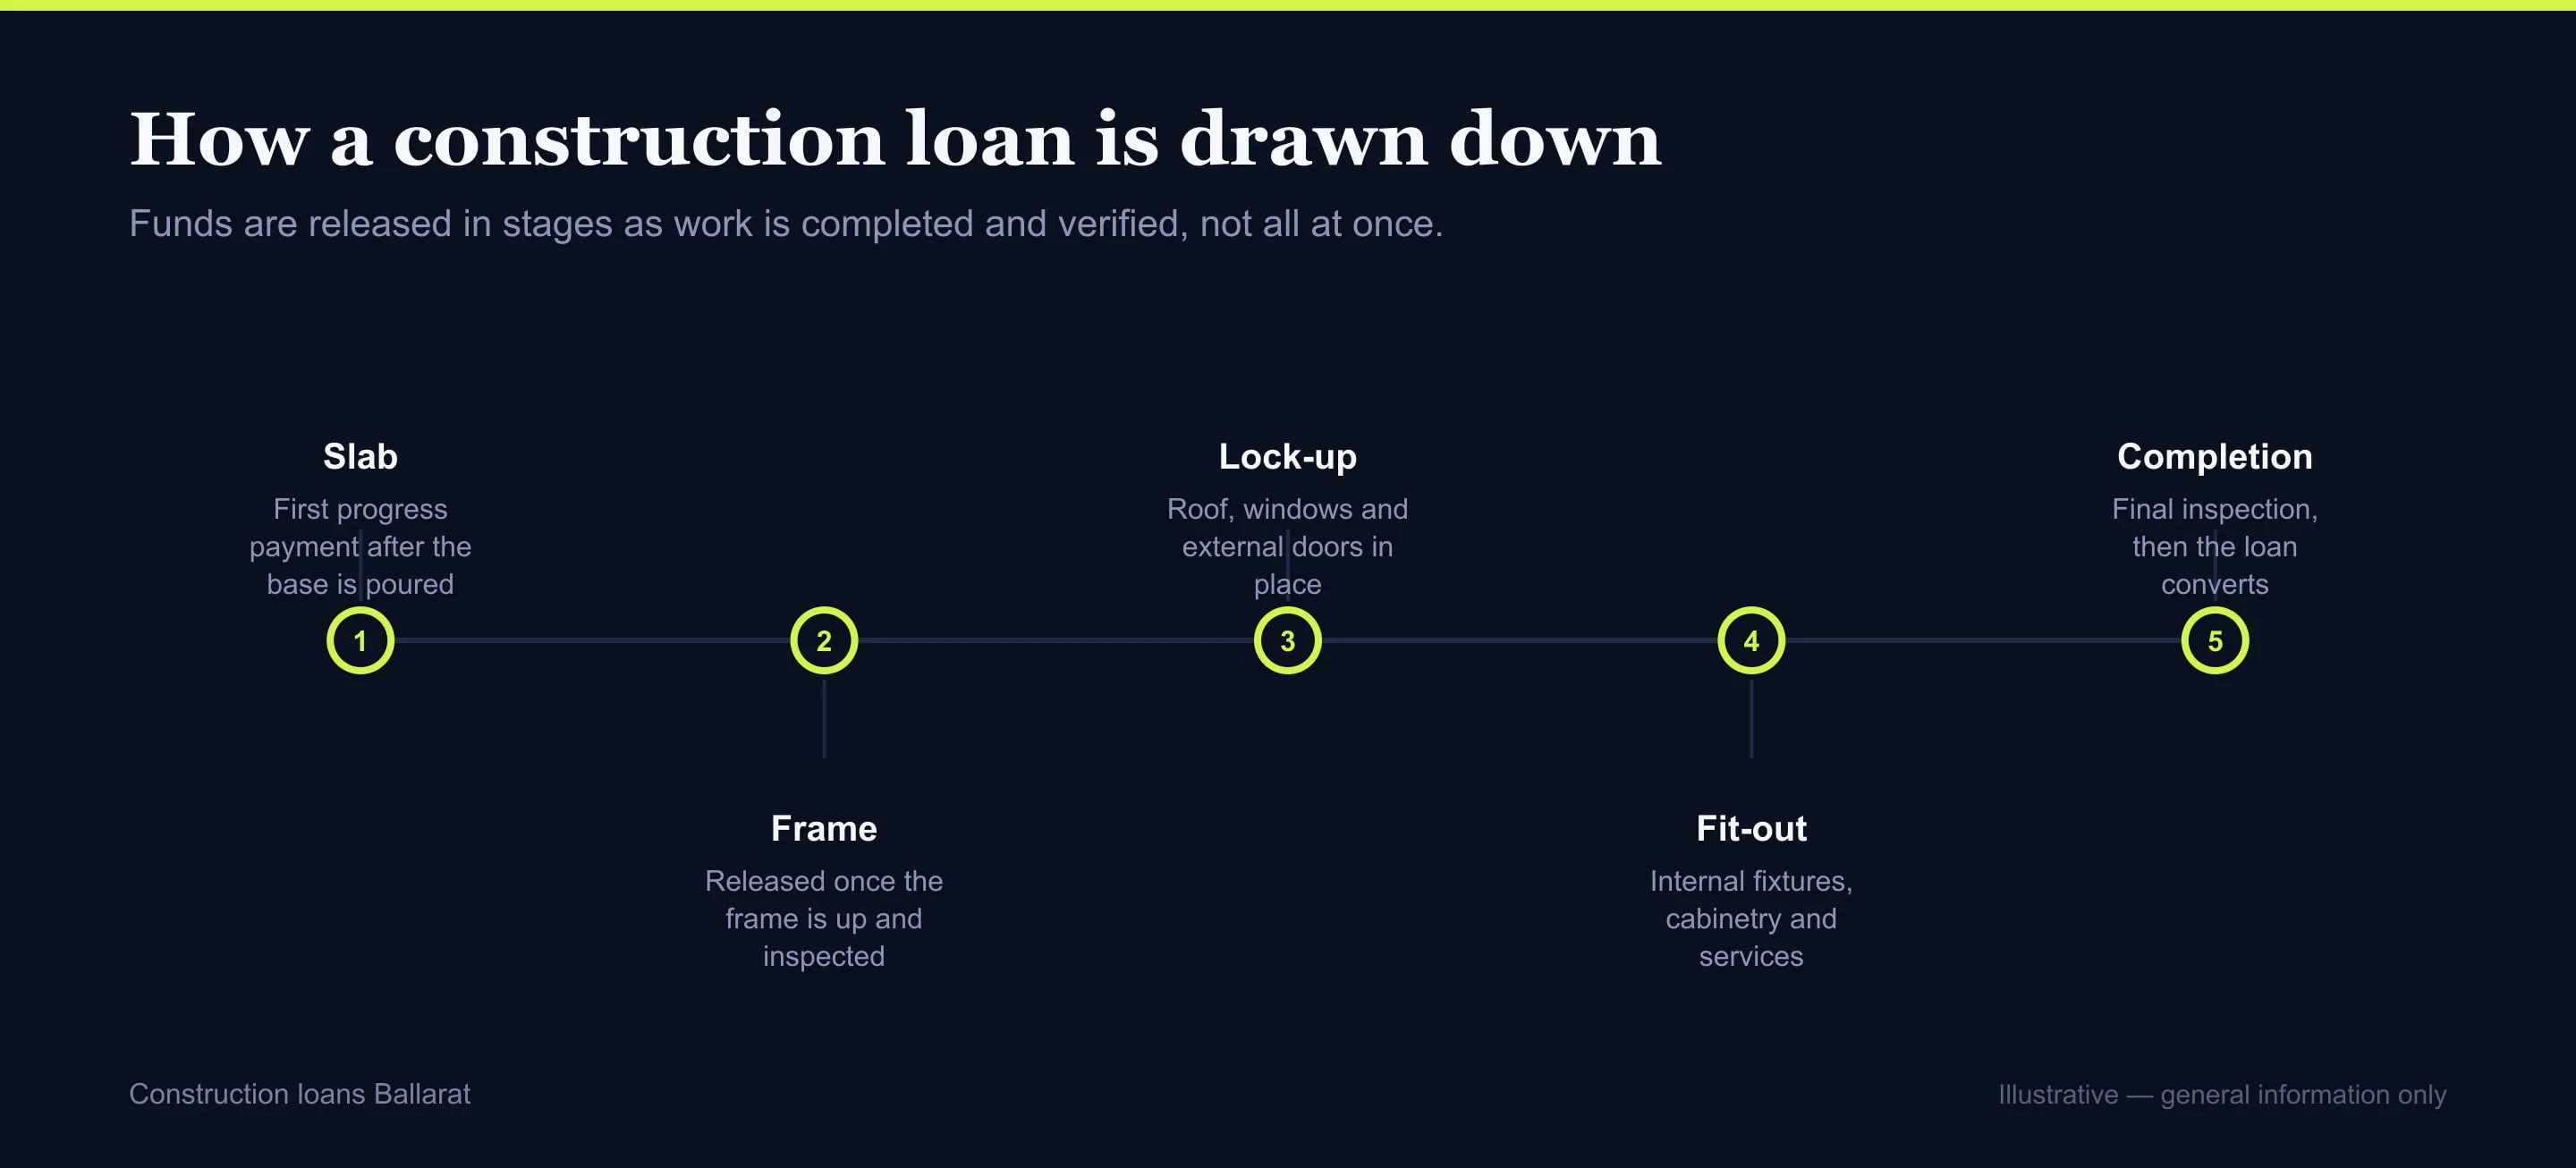
Your land settles first, then we draw the build component stage by stage, from base and frame through lock-up and fixing to completion. We arrange the lender's inspection before each release so your builder is not left waiting. Inspectors covering Ballarat can take a few days at busy times, so we book each one as the stage nears rather than after the invoice lands.
-
04
We budget the overlap with you
Because interest is charged only on what has been drawn, your repayments climb through the build. We set your budget against the end of the build, when the drawn balance is highest and you may still be paying rent.
What We Need From You
- The signed building contract, or the draft if you have not signed yet
- Council-approved plans and the specification schedule
- Your builder's registration number and domestic building insurance certificate
- The land contract, or the title if you already own the block
- Recent payslips or business financials, and evidence of your deposit
Talk Through Construction Loans Ballarat
Tell us what you are building and with whom, and we will work out what you can borrow against the finished build, what the draws will cost you through construction, and whether the package sits under the scheme cap. Call us before you sign anything.
Related Lending
Before You Call
What do you need from me to get started?
Ideally the draft building contract and the plans, plus your income details and what deposit you have. If you have not chosen a builder yet, a rough package price and your land details are enough for us to tell you what you can borrow and whether the numbers work.
What happens if the lender will not fund my builder?
We tell you before you sign, and we check the panel for a lender who will. Some lenders hold views on particular builders and owner-builder work is far more restricted, which is exactly why we would rather see the contract early than after you are committed to it.
Will you come out to the site, and does that cost anything?
We will meet you at the display home, the block or your kitchen table anywhere in Ballarat, and there is no call-out fee for it. Much of a construction file runs on documents, so plenty of clients never need a meeting at all. It is entirely your call.
How Your Money Comes Out During the Build
The staged release is the defining feature of construction lending, and it changes how you have to plan your cash flow. We walk you through the draw schedule before you sign the contract rather than after the slab goes down.
Your schedule will typically run base or slab, frame, lock-up, fixing, then practical completion. Your builder invoices at each stage, the lender arranges an inspection or valuation to confirm the work is done, and the funds go directly to the builder. We manage those draw requests for you, because a stage invoice sitting unpaid while paperwork catches up is what stops a site.
Because interest accrues only on what has been drawn, your repayments start small and grow as the build proceeds. Most lenders charge interest-only through construction and convert to principal and interest at completion. We show you the repayment at each stage rather than just the first one.
The practical consequence for you is that through the build you are usually paying construction interest and, if you are renting, rent at the same time. That overlap runs for the length of the build, so we budget it with you from the start rather than letting it arrive as a surprise at lock-up. On a typical Ballarat build that is the better part of a year of carrying both.
What Your Lender Will Want Before Funding
Construction lending carries a documentation requirement purchase lending does not, and gaps in it are the most common cause of delay. We assemble it with you before we lodge rather than chasing it while your builder waits.
Lenders generally want a signed fixed-price building contract, council-approved plans and specifications, your builder's domestic building insurance certificate, and evidence the builder is registered. They value the property on the completed build, which is called the "as if complete" valuation. That is the figure we size your loan against, so your deposit is measured against land plus build rather than the land alone.
Your builder matters to the lender as much as to you. Some lenders hold views on which builders they will and will not fund, and owner-builder projects sit in a different and much more restricted category. We check your builder against lender policy early, because finding out after you have signed narrows your options badly. We see most of the volume builders working Ballarat regularly enough to know which lenders are comfortable with them.
The valuation is the other thing worth watching. Where a Ballarat estate is releasing land in stages, the "as if complete" figure a valuer puts on your finished house can come in under the contract price simply because there are few completed comparable sales in the street yet. If that happens we take it up with the lender, and where it will not move we know which lenders on the panel take a different view.
Construction Loans Ballarat Growth Estates Need
Most of the new construction we finance is in the Ballarat West Growth Area, where house-and-land packages are the standard route to a new home. We know how those packages are usually structured, which matters because the land and build components often settle months apart.
Two local points decide your finance and we check both up front. First, if you are relying on the federal 5% Deposit Scheme, the combined land and build price counts against the price cap, not the land price alone. We total the package before you commit, because settling on land comfortably under $650,000 and then finding the finished package sits above it takes the scheme away from you at the worst possible moment.
Second, only a new build qualifies you for the Victorian First Home Owner Grant; established homes do not. If you are a first home buyer, that $10,000 is a genuine argument for building, and it points squarely at these estates. We factor it into the deposit figure we give you rather than leaving you to claim it later and hope. It applies on a contract price up to $750,000, which the great majority of Ballarat house-and-land packages sit under comfortably.
Should You Build, or Buy Established?
Building gets you a new home to your specification, generally with lower maintenance for the first years, and it is your only route to the $10,000 First Home Owner Grant. In the Ballarat growth estates the land is level and the services are new, which keeps site costs more predictable than an infill block closer to the centre.
Buying established gets you a settled street, mature trees, and certainty about what you are getting on the day you sign. There is no construction period to fund, no builder risk, and no gap between paying and moving in. If that suits you better we will arrange an ordinary home loan instead and say so.
The finance point that tips it for most of the people we talk to is the overlap: through a build you carry construction interest and your current housing cost at the same time. We model that overlap for you before you commit, and if it looks uncomfortable we will tell you established is the safer structure regardless of the grant.
Construction Loans Questions
How do construction loan repayments work?
Interest is charged only on the funds drawn so far, so your repayments start small and increase with each progress payment. Most lenders charge interest-only during construction then convert to principal and interest at practical completion, and we show you the repayment at each stage rather than just the first.
What deposit do I need for a construction loan?
Your deposit is assessed against the "as if complete" valuation of land and build combined, not the land price. Below 20% generally means Lenders Mortgage Insurance, though guarantee schemes can apply if you are an eligible first home buyer building new. We work out which applies to you before you sign.
Can I use the 5% Deposit Scheme to build?
Yes if you are eligible, but the combined land and construction price has to fall under the $650,000 cap that applies in Ballarat. We total the whole package rather than the land alone, because that is the number the scheme is tested against.
What is a fixed-price building contract?
A contract setting your build price upfront, which lenders generally require because it gives them a defined figure to lend against. We read the variation and provisional-sum clauses with you. Those are where a fixed price moves, and where a loan sized to the contract stops covering the build.
What happens if the build runs over time?
You keep paying interest on the drawn amount for longer, and if you are renting that overlap extends too. Construction loans carry a maximum build period and exceeding it needs the lender's agreement, so we raise significant delays with them early rather than at the deadline.
Who Handles Your Draws
The person who answers is the one who checks your building contract against lender policy and then arranges each progress payment as your build reaches it. They book the lender's inspection as the stage nears, so your builder is not left waiting on a valuer.
That is the part of a construction loan that decides whether the build runs smoothly. Every draw needs an inspection before the money moves, and a file where somebody is watching the schedule is a file where the base, the frame and the lock-up do not each stall for a week.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
Most of the builds we fund sit in the Ballarat growth estates, though we do plenty further out. The time to call is before you sign the building contract.