Ballarat, VIC 3350
Self-Employed Home Loans Ballarat
We read your financials the way a lender will, find the add-backs that lift your assessable income, and put your file with the lenders who handle your structure well. Working out what your business will actually support costs you nothing.
Two years of tax returns is the standard ask, and the figure lenders read off them is your taxable income, not your turnover. Good accounting drives that number down, which is exactly what makes a profitable business look thin to an assessor. Add-backs are how we put the depreciation and the one-off costs back.
What We Do for Self-Employed Borrowers
If you are a sole trader, in partnership, or you run a company or trust, lenders read your income differently from a salaried applicant. There are no payslips, so they work from your financial statements and tax records. We translate those documents into the figure a lender will actually assess, which is rarely the figure you would guess from your profit line.
Your core difficulty is structural rather than anything to do with creditworthiness. Good tax management minimises assessable income and lenders assess on what you declared to the ATO, so the strategy that reduced your tax bill also reduced your borrowing power. We cannot undo that, but we can make sure every legitimate add-back is recovered and that your file goes to a lender who reads your structure properly.
That is why we would rather hear from you earlier than a salaried buyer would call. Your preparation window is longer, and decisions about which year to apply in and when your accountant lodges are worth making before you are house-hunting rather than during.
We do this work for owner-operators right across Ballarat and the surrounding shires, and we are happy to deal with your accountant directly wherever they are. Most of the file runs on documents rather than meetings, so it makes little difference whether you are in Wendouree or out past Creswick.
What It Costs You to Have Us Look
Nothing. We will read your financials, work out what a lender will count and tell you what you can borrow at no cost, with no call-out fee anywhere in Ballarat or the district. The lender pays us a commission only if your loan settles.
We disclose what we are paid in writing in the Credit Guide before you apply, across every lender we might recommend. On self-employed files it is worth knowing that the commission does not vary with how hard the file is. A complicated trust structure costs you no more to have arranged than a straightforward sole trader file.
We are happy to work directly with your accountant, and there is no charge from us for that either. What your accountant charges to prepare or bring forward financials is between you and them, and we will tell you when it is worth asking for.
How We Prepare Your Application
Your file is largely decided before it is lodged, so we start with the paperwork rather than the lender. You can stop at any stage without cost.
-
01
We read your financials the way a lender will
We take two years of business financials, personal returns and the matching notices of assessment and read them for assessable income rather than profit. This is where you find out what your file will actually support, and it happens before anything touches your credit file.
-
02
We identify and evidence your add-backs
Depreciation, one-off expenses, additional superannuation, interest on debt being paid out. We point to each one in your financials rather than asserting it, because lenders differ on what they will accept and an unevidenced add-back is simply ignored.
-
03
We choose the lender around your structure
Sole trader, partnership, company or trust. Some lenders handle each cleanly and some do not, and the gap between them on identical financials is wide enough to decide your outcome. We pick the lender to fit you rather than sending your file to whoever is cheapest this month. Nothing about that depends on the lender having a Ballarat branch, and several of the best on this kind of file have none.
-
04
We lodge with the gaps already closed
Your file will attract more questions than a salaried one. We answer them inside the submission rather than a fortnight later, which is most of what keeps a self-employed approval moving. If you are buying at a Ballarat auction, that preparation is also what gets you a fully assessed approval rather than a printout.
What We Need From Your Accountant
- Two years of business financial statements, or the most recent year if that is all that exists
- Two years of personal tax returns with the matching ATO notices of assessment
- BAS lodgements if your business is registered for GST
- Business bank statements for the last few months
- Details of equipment finance, overdrafts and any ATO payment arrangement
Talk Through Self-Employed Home Loans Ballarat
Tell us where you are up to and we work out what your financials will actually support, which add-backs we can recover, and which lenders suit your structure. Call us if you would rather talk it through. We work with self-employed borrowers right across Ballarat.
Related Lending
Before You Call
What do you need from me to get started?
For the first call, a rough idea of your turnover and net profit, your structure, and what deposit you have is enough for us to give you a working figure. If you want a firm number we will need two years of financials and notices of assessment, and we are happy to request them from your accountant directly.
What happens if my financials will not support the loan?
We tell you the number they do support and what would change it: another year of trading, a different add-back position, or waiting for your accountant to finalise the current year. We would rather give you a plan and a date than lodge a file that gets declined and leaves an enquiry behind.
How long does a self-employed application take?
Gathering the financials is usually the long part and it is largely in your accountant's hands; once we have them, expect a few weeks from lodgement to formal approval. We will give you a realistic date at the first call rather than an optimistic one.
Do you need to meet me at my business?
Only if you would like us to. We will come to your premises anywhere in Ballarat at no charge, or run the whole file by phone and email. For a self-employed application almost everything that matters arrives as a document rather than a conversation.
What We Will Need You to Produce
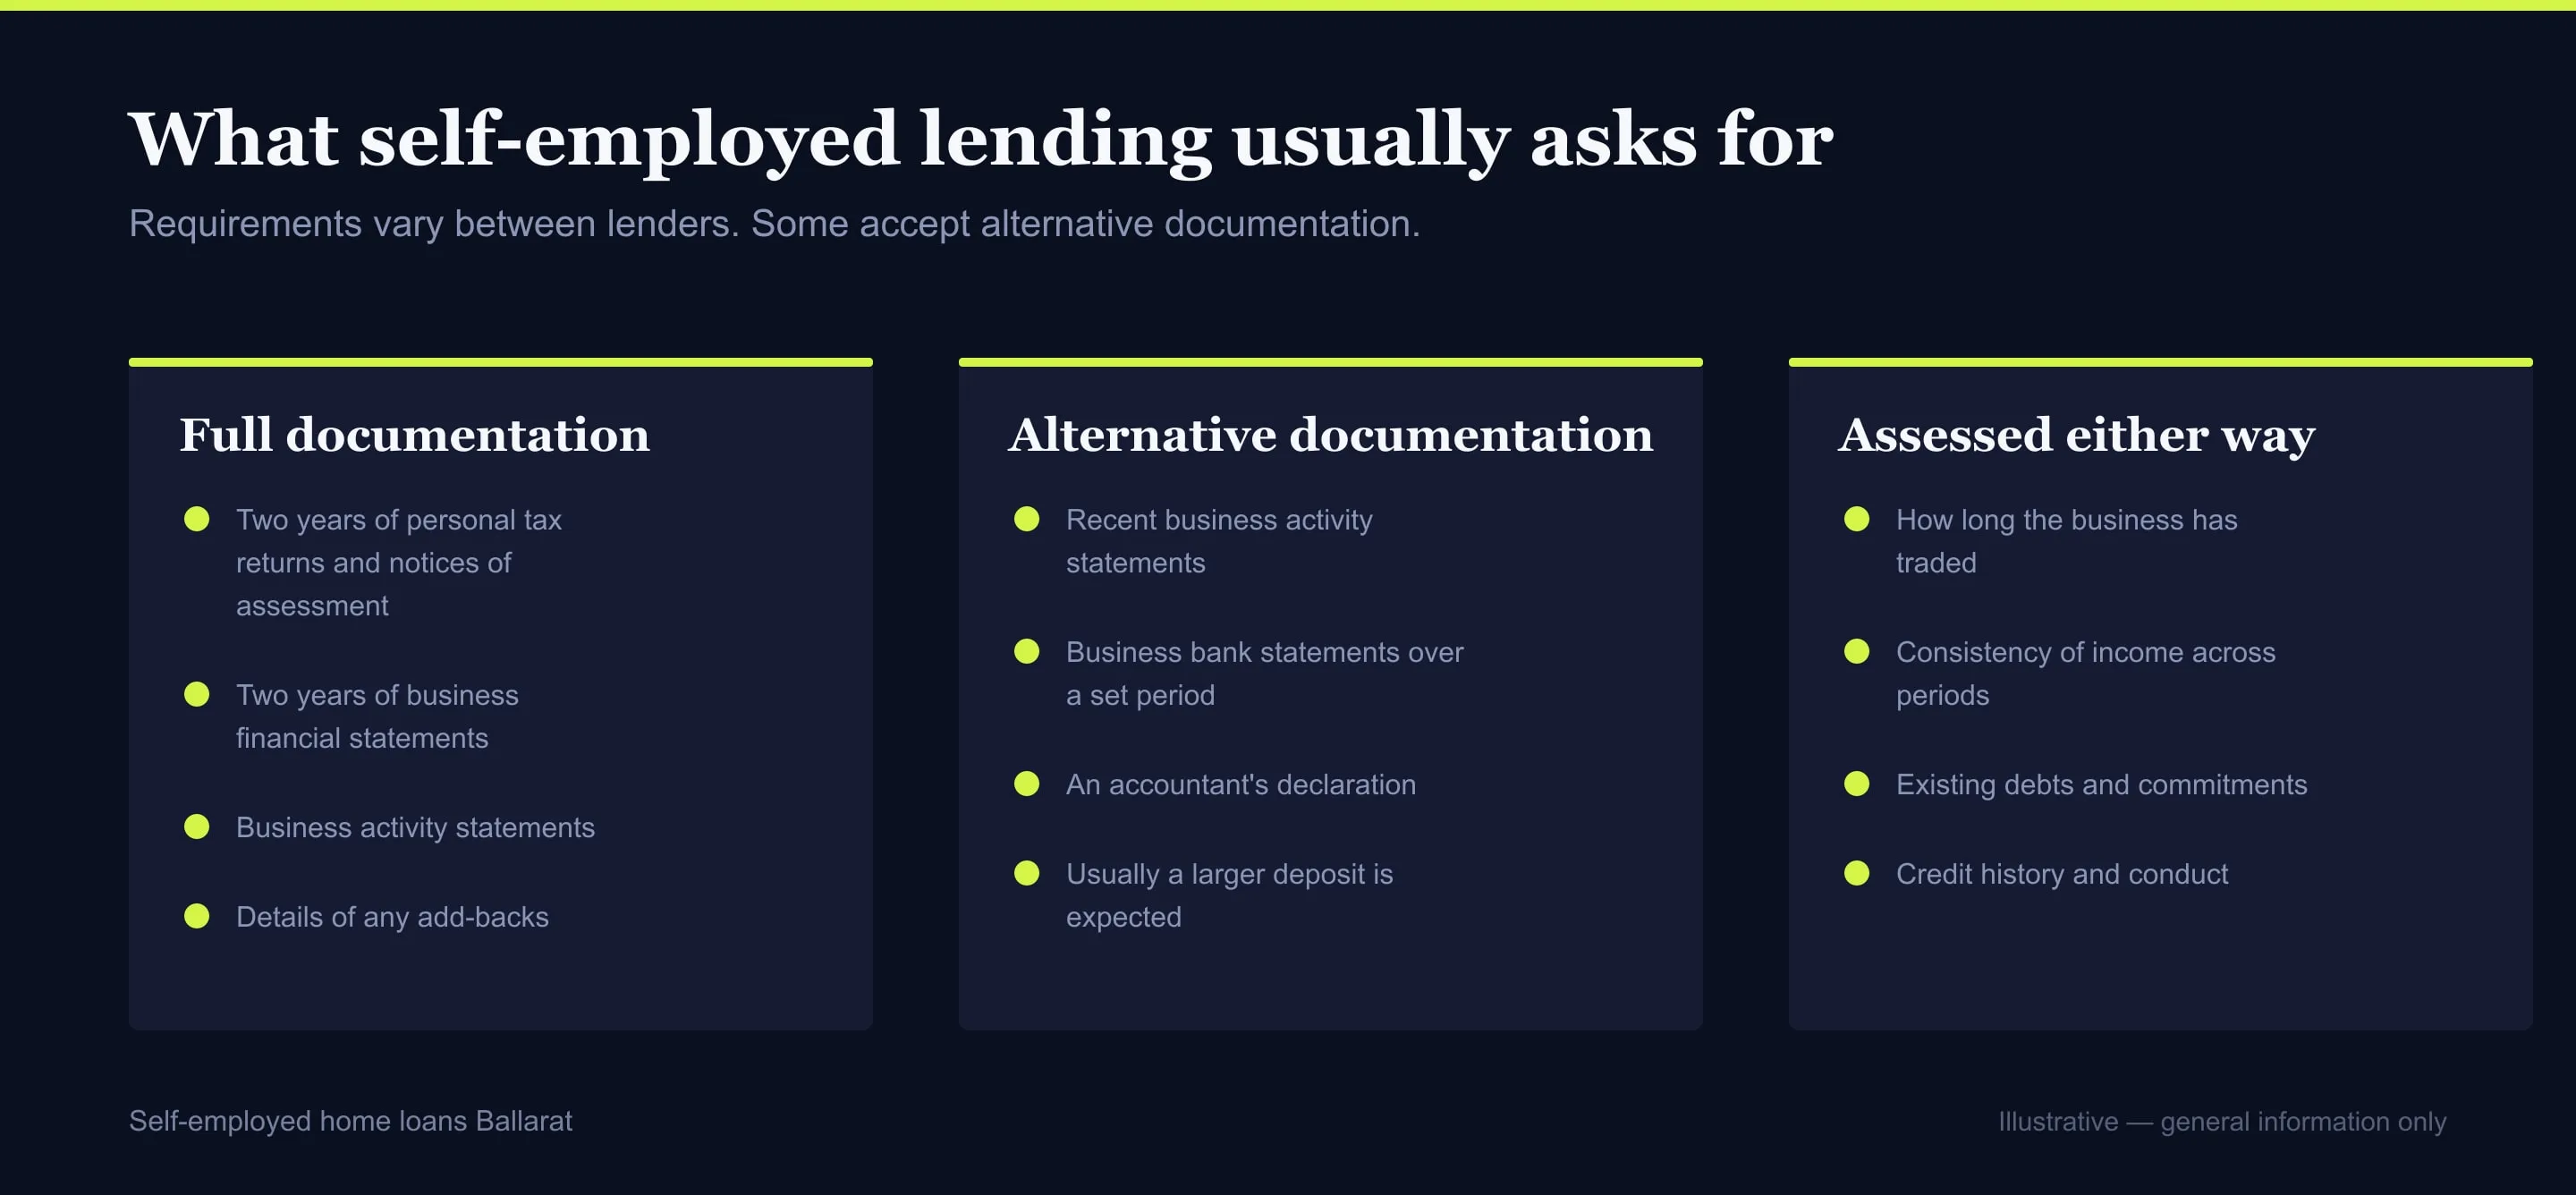
Documentation decides these files, and the standard requirement is more than you are likely to have to hand. We tell you exactly what to gather at the first call rather than discovering the gaps at assessment.
We ask for the full set upfront rather than in instalments. A partial file gets assessed slowly and questioned hard, and every round of questions adds a week.
A shorter trading history does not close the door, but it narrows the panel and the lenders still in it tend to want a larger deposit or price the loan tighter. We will tell you what that shortlist costs you against waiting, which matters most when you are newly out on your own.
When You Should Be Applying, and What to Tell Us
Where your income has grown year on year, most lenders average the two years rather than using the higher one; where it has fallen, they generally take the lower. That asymmetry decides which year you should be applying in, and we work it out with you before you commit to a timeline.
One thing worth saying to newer Ballarat operators in particular: an ATO payment arrangement does not automatically stop you. It has to be disclosed and it narrows the panel, but several lenders will proceed where the arrangement is being met and the underlying business is sound. Tell us about it at the first call rather than hoping it stays quiet, because it will not.
How We Rebuild Your Assessable Income
Add-backs recover income your tax return does not show, and applying them properly is the single most valuable thing we do on a self-employed file.
Certain expenses you deducted in your financials get added back to your assessable income because they are not genuine cash costs or are one-off. Depreciation is the clearest example, because it reduced your taxable profit without any money leaving the business. We also look for additional superannuation contributions beyond the required minimum, one-off or non-recurring expenses, interest on debts being refinanced or paid out, and net profit retained in a company.
Lenders differ substantially in which add-backs they accept and how they want them documented, so we point to each one in your financials rather than asserting it. A file where we have identified and evidenced the add-backs is assessed on a materially higher income figure than the same file lodged as raw tax returns. That difference is often the whole loan.
Self-Employed Home Loans Ballarat Businesses Get
A large share of the working population in Ballarat works for itself: trades servicing the growth estates, contractors, allied health practices, hospitality operators and farming businesses in the surrounding shires. We see all of them, and they hit the same assessment problem in different ways.
If you are a trade or construction contractor working the Ballarat estates, your income is often strong but seasonal with heavy equipment finance sitting against it, so how a lender treats that finance in the add-backs decides your outcome and we choose the lender accordingly. If you run a professional practice your financials are usually cleaner, but you may sit in a trust or company structure that some lenders handle badly, and we place those files with the ones that do it well. If your income comes from farming in the surrounding shires it varies year to year by nature, so we take you to lenders who understand agricultural cycles rather than ones who will read a lean year as a decline.
The common thread is that lender choice matters more for you than for almost any other borrower. The spread between the most and least accommodating lender on an identical set of financials is wide enough to decide whether your loan happens, and finding that spread is exactly what we are for.
The other thing working in your favour is the entry price. REIV put the median house price here at $610,000 in Q2 2026, so the income your financials have to demonstrate is materially lower than it would be for the same house in Melbourne. A business that would not support a metropolitan purchase quite often supports one in Ballarat comfortably. We will tell you which side of that line your figures fall on.
When We Use Low-Doc and Alternative Documentation
Where you cannot produce full financials, some lenders offer alternative-documentation lending and we will take you there. It is not the unverified lending of twenty years ago. Responsible lending obligations under the NCCP Act apply to these loans exactly as they do to any other, and we will still have to satisfy the lender you can afford the repayments.
Instead of tax returns, these lenders verify your income through business bank statements, BAS lodgements or an accountant's declaration, usually wanting more than one form of evidence. In exchange they generally require a larger deposit and price the loan above standard rates, so we only recommend this route when the full-doc path is genuinely closed to you.
It suits you if your business is trading well but your paperwork lags: a recently restructured entity, financials not yet prepared, or income that is real but awkward to evidence conventionally. If that describes you, we will tell you whether waiting for the paperwork would put you somewhere better, because often it would.
Should You Apply Now, or Wait for Another Year?
If your income is rising and you have one strong year behind you, waiting for a second can move you from a narrow set of lenders to the full mainstream panel, usually at better pricing. We will tell you when the delay is worth it rather than lodging you into the narrow set because you are ready today.
If your most recent year is weaker than the one before, the arithmetic reverses and we would rather get you in while the stronger year is still inside the assessment window than watch it drop out. That timing call is one of the few places a few weeks genuinely changes your outcome.
Your other lever is your accountant. Financials that have not been prepared cannot be assessed, and lodgement timing decides which years are available to us. We coordinate with your accountant rather than treating the loan and the tax work as separate exercises. We deal with most of the Ballarat accounting practices regularly and are comfortable requesting the documents directly.
Self-Employed Home Loans Questions
How long do I need to be self-employed to get a home loan?
Most mainstream lenders want two years of financials. Some accept one year for an established business, and a smaller group will consider six to twelve months of ABN and GST registration, typically with a larger deposit. We will tell you which of those groups you currently sit in.
What are add-backs?
Expenses deducted in your financials that lenders add back to your assessable income because they are not genuine cash costs: depreciation, additional superannuation, one-off expenses, interest being refinanced and retained company profit. Lenders differ in which they accept, so we evidence each one against the lender we are lodging with.
Can I get a loan with only one year of tax returns?
Some lenders allow it where your business is established and the income is clear, but fewer offer it so the comparison set is narrower. That is exactly the situation where checking policy across a panel changes the answer, and it costs you nothing to have us check.
What is a low-doc loan?
Lending that verifies your income through business bank statements, BAS or an accountant's declaration rather than full tax returns. Responsible lending obligations still apply, because it is alternative documentation rather than reduced scrutiny. You should expect a larger deposit and higher pricing, so we treat it as a route to use when the full-doc path is closed.
Does minimising my tax hurt my borrowing power?
Generally yes, because lenders assess the income you declared to the ATO. Add-backs recover part of the gap and we will recover everything legitimately available, but the tension is real and worth planning for well before you apply. That is why we would rather hear from you a year out than a month out.
Who Reads Your Financials
The person you speak to is the one who goes through your business financials line by line, identifies the add-backs a lender will accept, and evidences each one against the specific lender we lodge with. They also deal with your accountant directly when documents are outstanding.
They also know which lenders read a trust or a company cleanly and which do not, and that placement decision is made before anything is lodged rather than after a decline. A lot of Ballarat trades and contractors are knocked back at one lender and approved at another on the same set of numbers.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
A good share of our clients work for themselves, in Ballarat and the towns around it. Call before your accountant finalises the year if you can.