Ballarat, VIC 3350
Investment Property Loans Ballarat
Your rent will not count for as much as you think. Most lenders take about eighty per cent of it and shade the rest out, and the shading rate is not the same at every lender. That gap is often the whole difference between a purchase that services and one that does not, so we run your figures across a panel before you make an offer. It costs you nothing.
The other decisions come in pairs and each one has a cost attached: interest-only against principal and interest, one security against two tied together. We settle those with you at the outset, because unpicking a structure later is far harder than choosing it now.
What We Arrange for Investors
We fund property you intend to rent out rather than live in. Lenders classify that separately from the moment you apply and the classification affects both pricing and policy, so we set the file up as investment lending from the outset rather than having it reclassified mid-assessment.
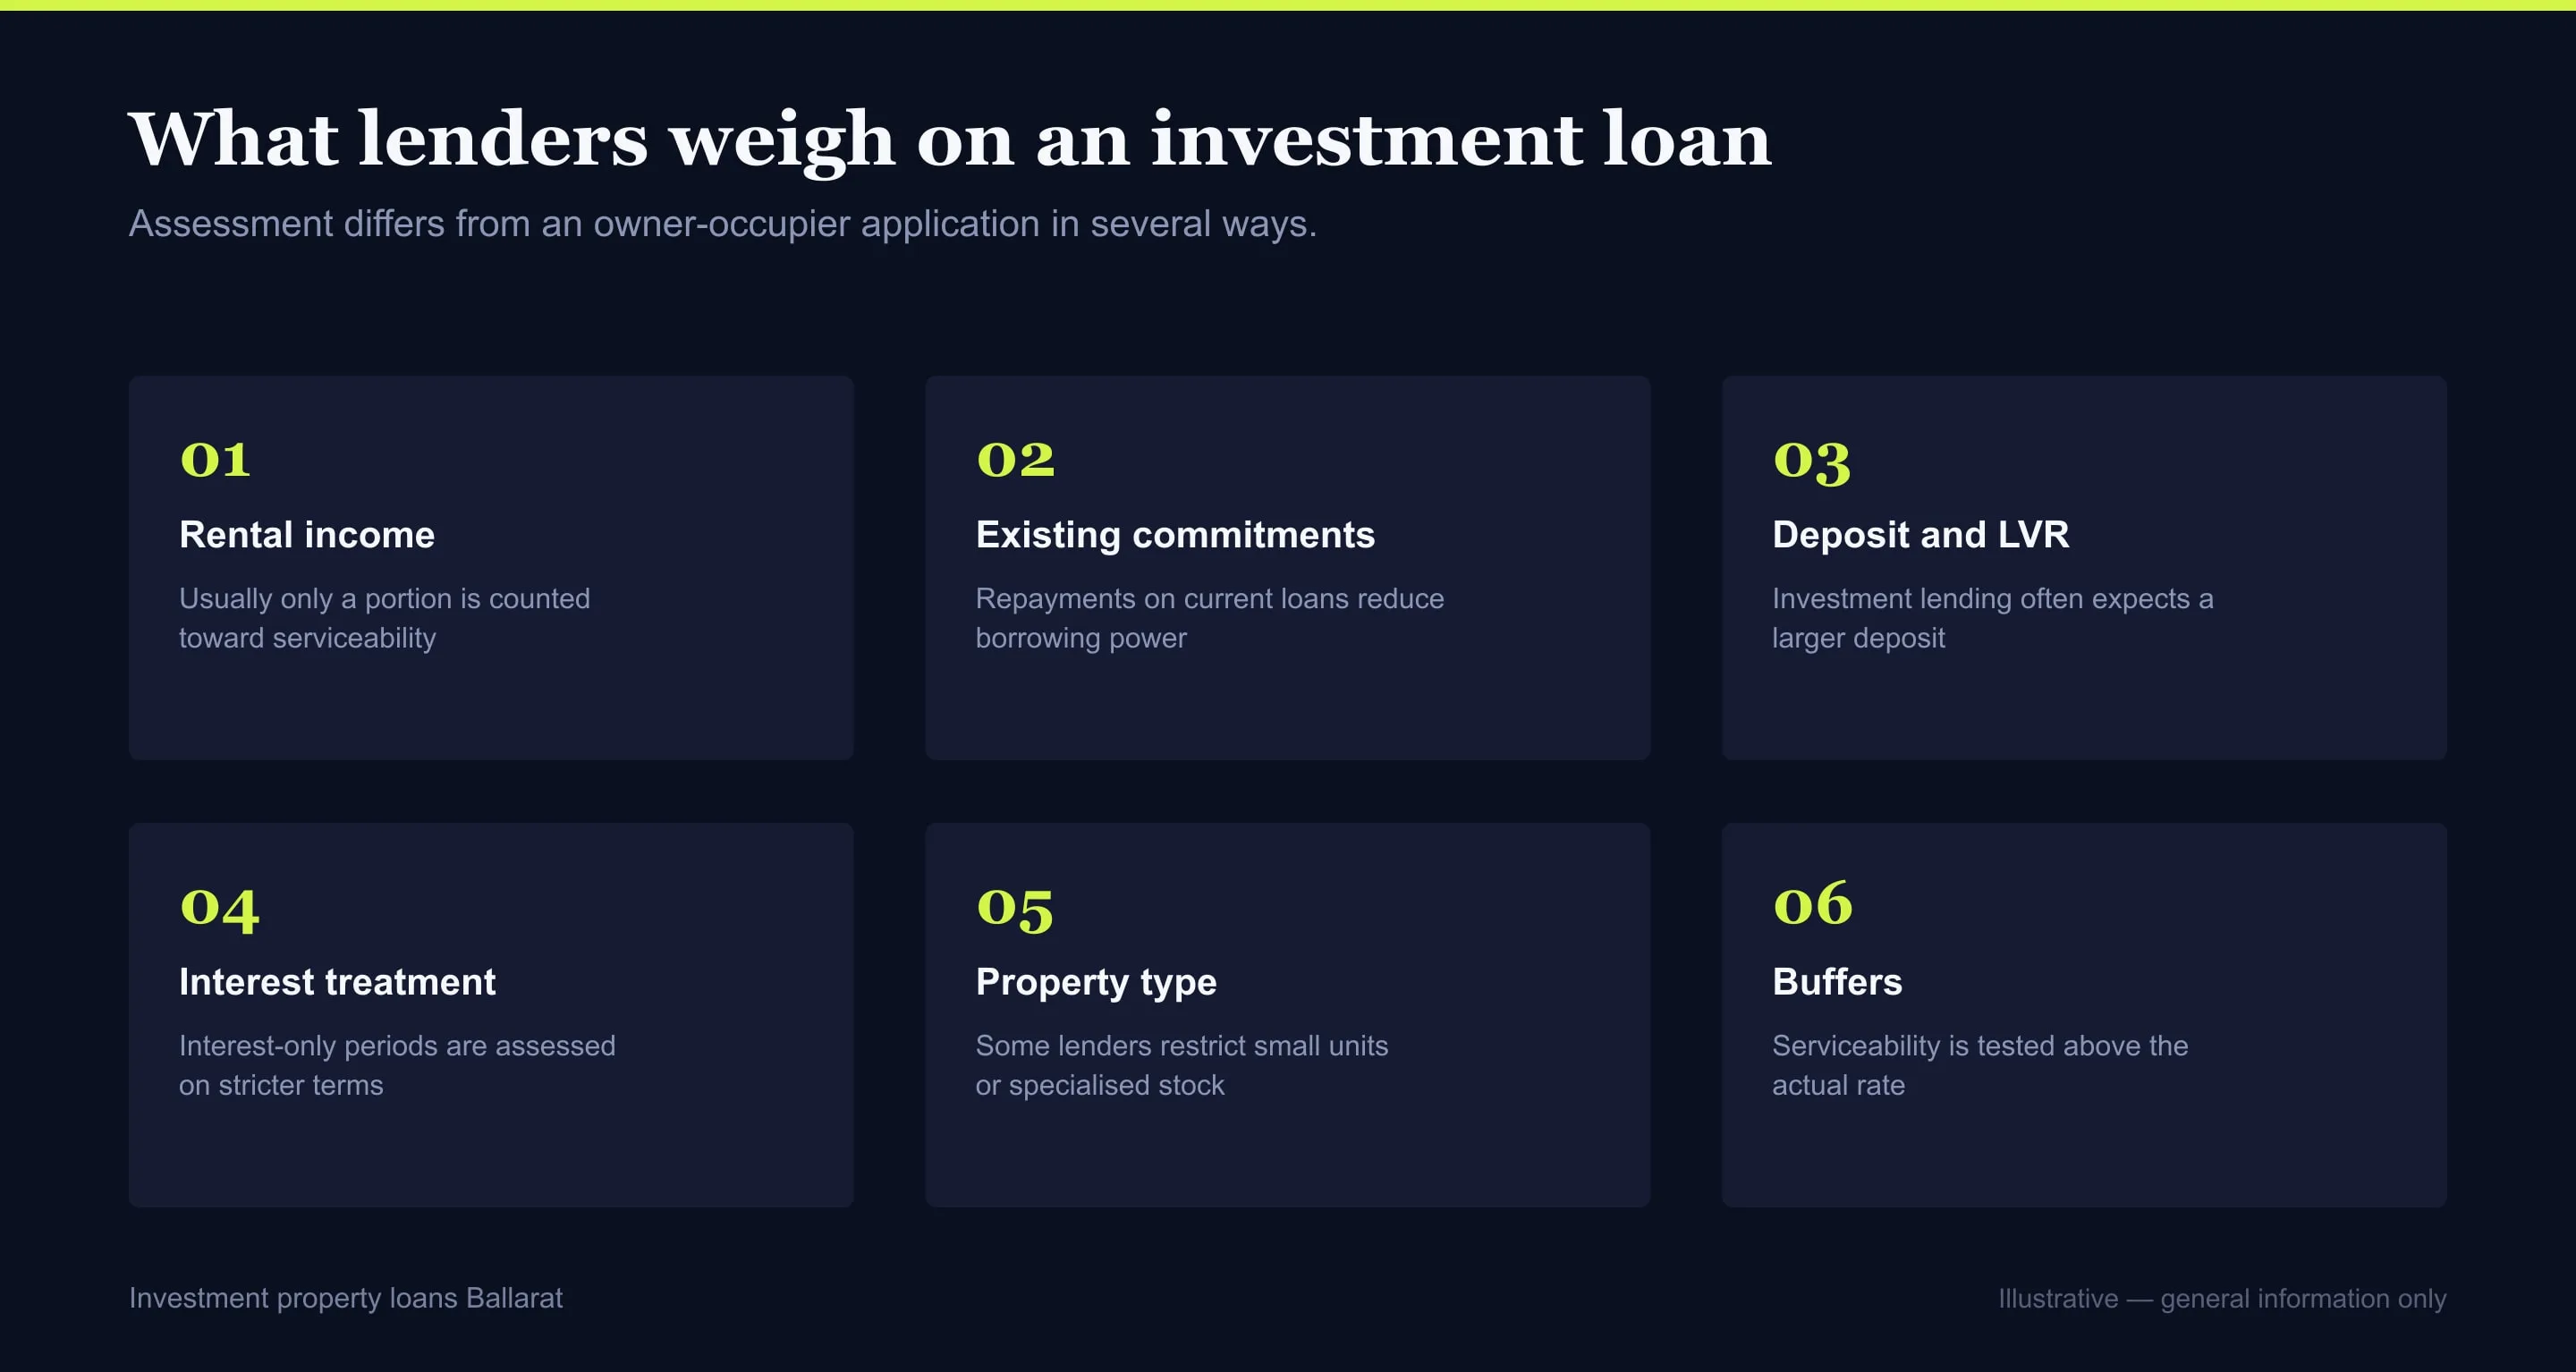
The income side is where the difference bites. Your salary counts as it does for any loan, and the expected rent is added on top, but never in full. How much of it survives is a policy setting rather than a market fact, and it is set by whichever lender you happen to apply to.
Your equity picture is different too. If you are buying a second property using equity in the first, the assessment covers both loans, both properties and your combined debt position. We look at your whole position rather than the new purchase in isolation.
Most of the investors we work with are buying in Ballarat itself, though we also fund purchases if you live here and buy elsewhere, and for Melbourne buyers coming the other way. Wherever you live, we work off the rental evidence for the suburb you are actually buying in.
What the Modelling Costs You
Nothing. We model the purchase across lenders, work out what rent will actually be counted and tell you what you can borrow at no cost, and there is no call-out fee anywhere in Ballarat or the surrounding shires. The lender pays us a commission only when a loan settles.
We disclose what we are paid in writing in the Credit Guide before you apply, across every lender we might put you with. If a fee ever applied to your file you would see it there first, before you were committed to anything.
One thing we do not do is tax advice. The tax treatment of an investment property is specific to your circumstances and belongs with your accountant. We will work alongside them on structure, but the information here is general and you should not treat it as tax advice.
How We Model Your Purchase
We do this before you start looking, because the rent a lender is willing to count decides what you can afford. You can stop at any stage without cost.
-
01
We model it across several lenders
We run the same purchase through the shading and the buffer each lender applies. The spread between the most and least accommodating is routinely wide enough to decide whether your purchase happens at all, which is why we do not rely on one.
-
02
We settle the security structure with you
Whether you use equity in your home, a separate cash deposit or both, and whether the lender takes both properties as security for both loans. We arrange this now because unpicking it when you want to sell one is slow and sometimes expensive.
-
03
We fix the repayment structure
Interest-only or principal and interest, and for how long. We will bring your accountant into this conversation, because the tax treatment is specific to you and we do not give tax advice.
-
04
We apply, value and settle
We lodge your application with a rental appraisal attached, manage the lender's valuation, and run the loan through to settlement. Valuers covering Ballarat book out when the market is busy, so we order early rather than waiting for the lender to get to it.
What We Need From You
- Statements for your existing home loan and any other property debt
- Recent payslips or business financials
- A rental appraisal for the property, or comparable rents if you are still looking
- Council rates, insurance and owners corporation costs where they apply
- Your accountant's details, if the purchase is likely to sit in a trust or company
Talk Through Investment Property Loans Ballarat
Tell us where you are up to and we work out what you can borrow, how much rent each lender will actually count, and what the security structure should look like. Call us if you would rather talk it through before you make an offer.
Related Lending
Before You Call
What do you need from me to model a purchase?
Your existing loan statements, recent payslips or business financials, and either a rental appraisal or comparable rents for the area you are looking at. That is enough for us to tell you what you can borrow and which lenders will count the rent most generously.
How long does an investment loan take?
Commonly a few weeks from lodgement to formal approval, with the lender's valuation the step most likely to add time. If you are buying at auction we would rather have you modelled and pre-approved first, and we will tell you how long that takes for your situation.
Do I need to live in Ballarat to buy an investment here?
No. We arrange investment lending for buyers based in Melbourne and interstate as often as for local owners, and the file runs by phone and email either way. What we do insist on is a written rental appraisal from an agent who works the suburb, because that is what the lender will count.
How Much of Your Rent a Lender Will Count
This mechanic decides whether your purchase is actually affordable, and it is the one that surprises people most, so we work it out before you go looking rather than after you have made an offer.
Lenders do not count your gross rent. They shade it, typically counting around 80%, to cover vacancy periods, property management fees, rates, insurance and maintenance. The exact figure varies by lender and sometimes by property type. We use each lender's actual shading rather than a rule of thumb, because the difference between them is often the whole margin.
On top of that shading, the new loan is assessed at the serviceability buffer rate like any other, and any existing mortgage you hold is assessed at its own buffered rate too. If you already carry an owner-occupied loan you are assessed as though both loans cost substantially more than they do, which is why the figure we give you is lower than an online calculator will suggest.
Because the shading percentage differs between lenders, the same Ballarat purchase can be serviceable at one and not at another on identical figures. Comparing policy rather than rate is where we earn the commission, and it is not work you can do from published rate tables.
Rent evidence matters as much as the shading percentage, and it is the part we can influence. A lender will accept a managing agent's written appraisal for a Ballarat property far more readily than your own estimate, so we ask for one before we lodge and we make sure it reflects what comparable properties in that street are actually letting for.
Choosing Between Interest-Only and Principal and Interest
Interest-only periods are more common on investment lending than on owner-occupied loans, usually for cash-flow and tax reasons, and we settle which one suits you before we lodge rather than accepting the lender's default.
Paying interest only keeps your repayments lower during the period, which improves cash flow while you hold the property. The trade-offs are real and we put them in front of you: you are not reducing the debt, the rate is usually higher than the equivalent principal-and-interest rate, and when the interest-only period ends your repayments step up sharply because the same principal now has fewer years to amortise over.
Lenders also assess interest-only loans on the principal-and-interest repayment over the remaining term, not on the lower interest-only repayment. So choosing interest-only will not increase your borrowing power, and we will tell you that if it is the reason you were considering it.
Whether the structure suits you is a question for your accountant as much as for us. We are happy to model the repayment outcomes either way and hand those numbers to them, but the tax treatment is specific to your circumstances and this is general information rather than tax advice.
Investment Property Loans Ballarat Landlords Use
What brings you to us is usually the gap between entry price and rental return in Ballarat. With house prices well below metropolitan Melbourne and a rental market supported by Federation University, the Base Hospital and steady population growth out of the capital, gross yields have generally compared favourably, at around 3.4% on recent figures with vacancy running between 0.8% and 1.4%. We check those numbers against current listings for your specific suburb rather than quoting the city-wide average at you.
The tenant base is genuinely mixed rather than tied to one employer. Health, education, retail, manufacturing and government all feature, which matters to you for vacancy risk and matters to the lender for how it views the security. Suburb choice still drives your numbers, so we look at where you are buying. The established areas near the centre, the growth estates on the western edge and the university corridor behave differently as rental propositions, and lenders read them differently too.
Entry price is the other half of it. With the median house price at $610,000 on REIV's Q2 2026 figure, well under the metropolitan equivalent, the equity you already hold generally stretches further here than it would in Melbourne. That, rather than yield, is usually what makes your first investment purchase possible. We work out how far yours goes before you start looking.
None of that is a forecast and we will not present it as one. Yields and vacancy rates move, past growth does not predict future growth, and we will have you check any figure in an agent's listing independently before you rely on it in your own numbers.
Should You Buy Through Equity, or Save a Separate Deposit?
Using equity in your home avoids saving a fresh deposit and is usually the faster route, and we can tell you within a call whether you have enough of it. The cost is that your home then secures borrowing against an investment, so a problem with the investment reaches your home. We would rather you decided that with your eyes open than discovered it later.
A separate cash deposit keeps the two properties independent. It takes you longer to assemble but leaves a cleaner structure, and plenty of the Ballarat investors we work with prefer that separation regardless of what the arithmetic says.
There is also a cross-collateralisation question, which is whether the lender takes both properties as security for both loans. It can simplify your approval and complicate everything afterwards, particularly when you want to sell one, so we settle it deliberately with you rather than letting the lender's default decide it.
Investment Property Loans Questions
How much rental income do lenders count?
Not all of it. The shading is set by each lender rather than by the market, so the same purchase can service at one and fail at another on identical figures. We model yours across the panel before you offer, and a written appraisal from an agent who works the suburb is what gets the rent counted at the top of that range.
Can I use equity in my home as the deposit?
Commonly, yes. The lender assesses your combined position, meaning both loans, both properties and your total debt. It is a full application rather than an automatic extension of the loan you already have. We check whether you have enough usable equity before you go any further.
Do investment loans cost more than owner-occupier loans?
Investment lending is generally priced above owner-occupied lending, and interest-only above principal and interest. The exact differential depends on the lender and your loan-to-value ratio, and comparing that differential across lenders is part of what we do for you.
Is interest-only better for an investment property?
It improves your cash flow during the period, but the debt does not reduce, the rate is usually higher, and your repayments step up at the end. It also will not increase your borrowing power, because lenders assess the principal-and-interest repayment regardless. We will model both for you, and the tax side belongs with your accountant.
What yields do Ballarat investment properties achieve?
It varies by suburb, property type and the point in the cycle. Published figures are usually gross rather than net. Recent gross yields have sat near 3.4% with vacancy between 0.8% and 1.4%. We check any yield against current rental listings and the actual outgoings rather than letting you rely on a headline number.
Who Models Your Purchase
The person you speak to is the one who runs your figures across the panel, applies each lender's actual rental shading rather than a rule of thumb, and settles the security structure with you before anything is lodged.
That modelling is the part worth doing before you bid rather than after. The spread between lenders on how much rent they count is often the whole margin on whether a Ballarat purchase is serviceable, and cross-collateralisation is far easier to avoid at the outset than to unpick when you want to sell one property.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
Investors buy across the Ballarat district and further out, and we lend on both. Worth modelling the purchase before the auction rather than after.