Ballarat, VIC 3350
Home Loan Pre-Approval Ballarat
We get you pre-approved before you start bidding, in the fully assessed form rather than the automated one, so you know your ceiling and the lender has actually read your file. Working out your number costs you nothing and does not touch your credit file.
Two things get called pre-approval. One is a calculator output on lender letterhead, produced automatically, with nobody reading your file. The other has had a credit assessor verify your documents and make a decision. Only the second is worth bidding on, and we go after that one.
What We Get You Before You Bid
We get you a lender's indication of how much it is willing to lend, given your income, debts and deposit, before you have found a property. You will see it called pre-approval, conditional approval or approval in principle, and they mean the same thing.
The word doing the work is conditional, and we will not let you treat it as more than it is. The lender has assessed you but not the property, because there is not one yet. Your full approval only arrives once you have a specific property, the lender has valued it, and the final checks are done. We tell you plainly what your letter does and does not commit anyone to.
There is also a meaningful difference in how thoroughly the assessment was done, and it is not obvious from the letter you receive. We make sure you get the thorough kind, because that difference decides whether your approval survives an auction.
We get you approved right across Ballarat and the surrounding shires, and the number we give you is set against what property here actually sells for rather than a generic maximum. You will usually end up bidding well inside the figure an online calculator would hand you, which is a more comfortable position than it sounds.
What Getting Pre-Approved Costs You
Nothing. The borrowing-power conversation is free, and so is the work of preparing and lodging your pre-approval. The lender pays us a commission only if a loan eventually settles. There is no call-out fee anywhere in Ballarat or the district, and no charge if you decide not to buy.
We disclose what we are paid in writing in the Credit Guide before you apply, covering every lender we might use. Nothing about that changes depending on which lender you end up with, or on how large your loan is relative to your budget.
One thing does have a cost to you, though not in money: the application itself leaves a credit enquiry on your file. That is exactly why we run the numbers informally first and only lodge once we know which lender fits. You are not spending enquiries to find out what you could have been told for free.
How We Get You Approved
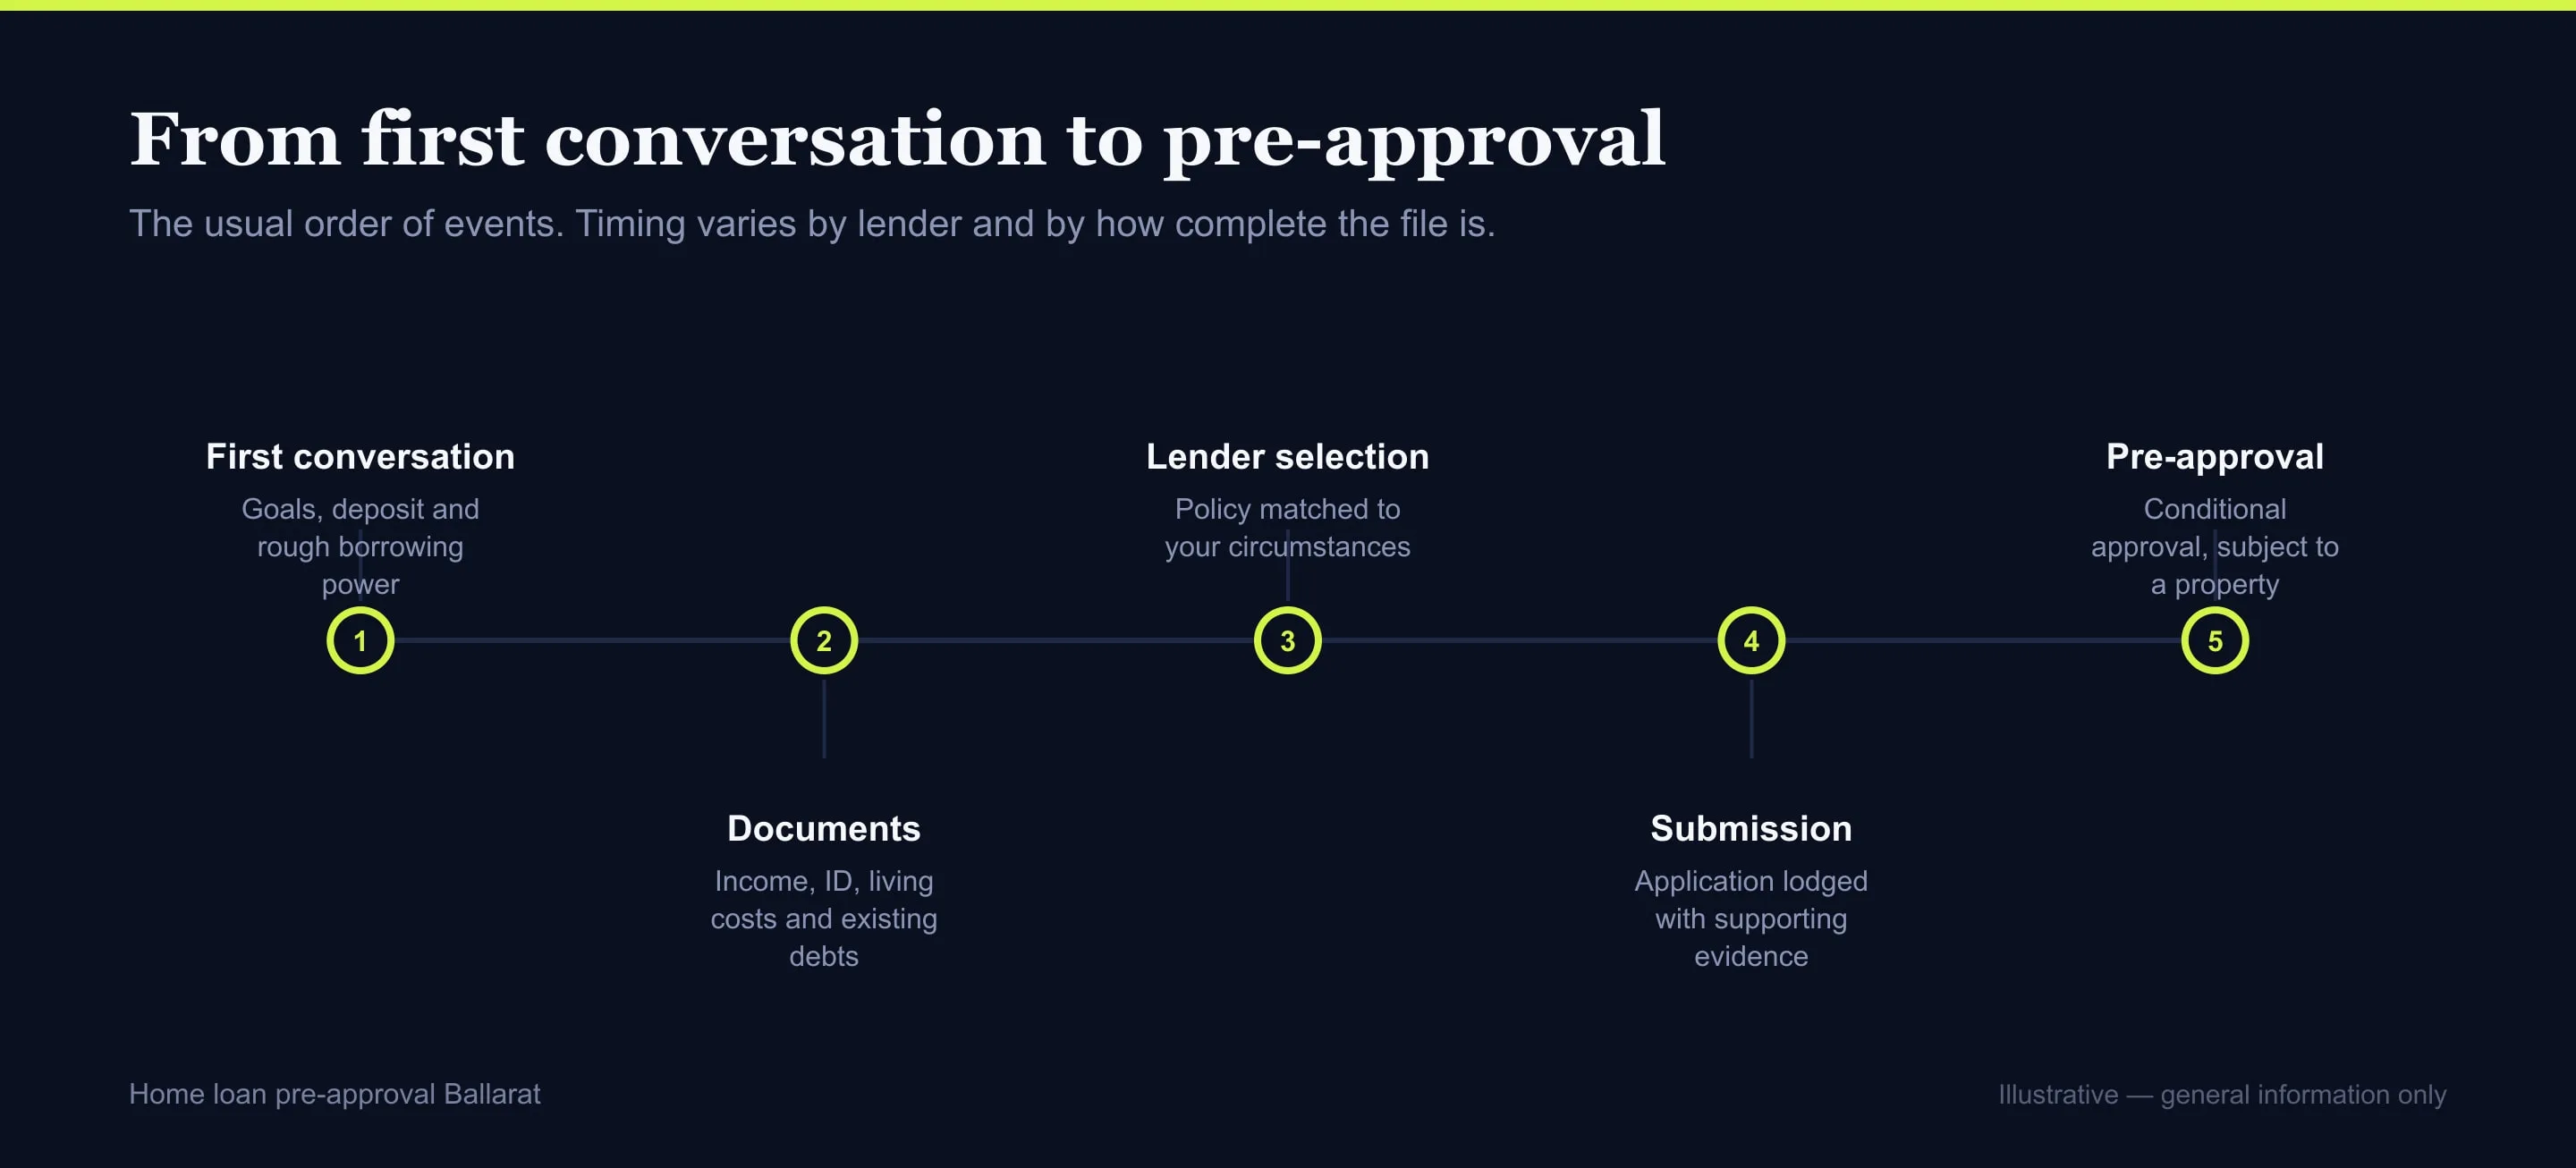
We do this properly when you genuinely intend to buy, and in the fully assessed form. You can stop after any stage without cost.
-
01
We start with a borrowing-power conversation
No application and no credit enquiry, just the number. If you are still deciding whether to buy at all, we will tell you to stop here until you are closer rather than spending an enquiry.
-
02
We choose the lender before we apply
Your application leaves an enquiry on your file, so we get it right the first time. We ask the lender which kind of approval it will issue you, and hold out for a fully assessed one if you intend to bid at a Ballarat auction.
-
03
We submit documents, not just figures
We give the credit assessor your actual payslips and statements so a person reads the file and makes a decision. That is the version that survives contact with an auction, and it is why we ask for the paperwork upfront.
-
04
We keep your position still
Approvals run around three months and get reassessed on renewal, so a new car loan, a new card or a job change can undo one. Ring us before you do any of those and we will tell you what it costs you.
What We Need From You
- Photo identification for every applicant
- Your last few payslips, or business financials if you work for yourself
- Statements for your everyday and savings accounts
- Limits and balances on your cards, and repayments on any loans
- Evidence of your deposit, including any gift or guarantor arrangement
Talk Through Home Loan Pre-Approval Ballarat
Tell us where you are up to and we work out what you can borrow, which lender will give you a fully assessed approval, and how long it will take. Call us before you start bidding. The borrowing-power conversation leaves nothing on your credit file.
Related Lending
Before You Call
What do you need from me to get started?
For the borrowing-power figure, just a rough picture of your income, debts, card limits and deposit. No documents and no enquiry. For a fully assessed approval we will need identification, payslips or business financials, account statements and evidence of your deposit.
What happens if I am not approved for what I need?
We tell you the figure you would be approved for and what would lift it: closing a card, waiting out a probation period, or building more deposit. That advice costs you nothing, and we would rather give you a plan than lodge an application that fails and leaves an enquiry behind.
How quickly can you get me pre-approved?
Once we have your documents, a fully assessed approval commonly takes a few business days to a couple of weeks depending on the lender's queue. If you have an auction date in mind, tell us at the first call and we will pick the lender partly on turnaround.
Do we need to meet in person?
Not unless you want to. We will meet you anywhere in Ballarat at no charge, and we can equally get the whole approval done by phone and email. Identification can be verified electronically, so nothing about the process requires you to sit across a desk from us.
How Long Yours Will Last
Your pre-approval has a shelf life and it is shorter than you would plan for, so we time it against when you actually expect to buy rather than getting it the moment you start thinking about it.
Most run around three months and then lapse. We can usually renew or extend one for you, but the lender will want updated payslips and bank statements and it reassesses on your current position rather than the one you presented originally. A renewal is not a formality, and we would rather you knew that going in.
Because you get reassessed, what you do during the search period matters. Changing jobs, taking on a car loan, opening a new credit card or a drop in income can all reduce or remove an approval that previously stood. So we ask you to keep your financial position still between approval and settlement, and to ring us before you do any of those things rather than after.
Timing is the other reason to talk to us early. If we get you approved before you are genuinely ready to buy, it will lapse mid-search and have to be redone, which costs you another enquiry for nothing. Three months is a realistic search window in Ballarat if you are genuinely looking, and a very short one if you are still deciding whether to buy at all.
Why We Insist on a Fully Assessed Approval
This distinction is the single most useful thing we can tell you about pre-approval, and it explains why plenty of pre-approved buyers still get declined.
A system-generated pre-approval is produced automatically from the figures entered, with no human assessor reading the file and no documents verified. It is fast and it is weak, being a calculator output on lender letterhead, and we will not let you bid at auction on one.
A fully assessed pre-approval means a credit assessor has reviewed your actual documents, verified your income and made a decision. It takes us longer to obtain and it carries far more weight, because the underwriting has genuinely been done. That is the version we push for, and it is a large part of why we prepare your documents properly before lodging rather than just keying in numbers.
Both arrive as a letter and both get called pre-approval, so we tell you which one you are holding. If you are bidding where there is no cooling-off period and no finance clause, the difference between them is the difference between a manageable risk and a serious one, and you are entitled to ask us directly which kind yours is.
It also affects how an agent reads you. Ballarat selling agents see approval letters constantly and the good ones know the difference, so a fully assessed letter does more for your offer than a printout does. That matters most when a vendor is weighing two similar offers and choosing on which one is likeliest to settle.
Home Loan Pre-Approval Ballarat Auctions Demand
Being pre-approved changes how you can act. You know your ceiling, you can move quickly on a property you want, and Ballarat agents take you more seriously than they will take someone who has not started the finance conversation. We get the letter into your hands before you are competing for something.
We set that ceiling against what this market actually asks of you rather than a generic maximum. REIV put the local median house price at $610,000 in Q2 2026, and stock moves quickly here, with HTAG putting the median time on market at around 21 days in 2026. So we work out what you can commit to before the property you want appears, not while you are trying to decide on it.
The auction point is the one we press hardest. At auction there is no cooling-off period and no subject-to-finance clause, and the contract binds you on the fall of the hammer. If you bid on a system-generated approval and the finance does not eventuate, your deposit is at risk. Private sale contracts in Victoria generally allow a finance condition, which is a materially safer position, and we will tell you which situation you are walking into before you raise your hand.
Pre-approval also does not remove valuation risk, and we would rather you heard that from us than from a valuer. If the lender values the property below what you agreed to pay, the shortfall is yours to cover regardless of how comfortable your letter looked. That risk is worth taking seriously in the Ballarat growth estates and on acreage, where comparable sales are less uniform. We factor that gap into the ceiling we give you rather than sending you out to bid at your absolute maximum.
Should You Get Pre-Approved Now, or Wait?
Getting pre-approved first is the stronger position in almost every case. You know your budget, you can bid with confidence, and you are not scrambling for finance while a vendor weighs other offers. That is what we will normally recommend.
The argument for waiting is that approvals lapse and each application leaves a credit enquiry, so getting you approved a year before you are ready achieves nothing. If you are still deciding whether to buy at all, we will give you an informal borrowing-power figure instead, which costs you no enquiry and no money.
The sequence that works for most Ballarat buyers we deal with is a borrowing-power conversation early, then a fully assessed pre-approval once you are genuinely looking and expect to buy within the next few months. We are happy to have the first conversation now and hold off on the second until you say the word.
Home Loan Pre-Approval Questions
How long does pre-approval last?
Usually around three months. We can generally renew it, but the lender reassesses on your current position with updated documents, so a change in your circumstances can affect the outcome. That is why we time the application against when you actually expect to buy.
Is pre-approval a guarantee I will get the loan?
No, and we will not present it as one. It stays conditional throughout, subject to a satisfactory valuation, final verification and the lender's credit policy at the time. It indicates your capacity; it does not commit the lender to fund.
What is the difference between conditional and unconditional approval?
Conditional approval, or pre-approval, is issued before you have a property and remains subject to conditions. Unconditional or formal approval comes after a specific property has been valued and every condition satisfied. That is the point at which the lender is committed, and we will tell you clearly when you have reached it.
Can I bid at a Ballarat auction with pre-approval?
You can, but auction contracts in Victoria are unconditional: no cooling-off period and no finance clause. We will only be comfortable with you bidding on a fully assessed approval rather than a system-generated one, and even then a low valuation leaves you covering the difference, so we set your ceiling below your absolute maximum.
Does getting pre-approved affect my credit score?
The application usually creates one credit enquiry, which has a modest effect on its own. Repeated applications to several lenders in a short period have a larger one, which is why we identify the right lender before lodging rather than testing the market with your file.
Who Gets Your Approval Assessed
The person you speak to is the one who prepares your documents properly and pushes for a fully assessed approval rather than a system-generated printout. That means a credit assessor has verified your income and made a decision before you go looking.
That preparation is the whole difference between a letter that holds up and one that does not. It is also why we would rather run the numbers with you informally first: an application you were never going to proceed with still leaves an enquiry on your file.
-
Call
Quickest if you want an answer while you are still deciding. Monday to Friday, 9am to 5pm.
-
Form
Better if you are on shift, on site, or would rather write it down than talk it through.
-
Email
info@mortgagebrokerballarat.net.au
Use this when you have documents to attach: a contract, a payout figure, a listing.
Ballarat, VIC 3350
Where We Work
Buyers across the Ballarat district get approved through us before they start bidding. Worth a call as soon as you have an auction date in mind.